Solution
Reasoning for Calculations and Beneficial Regime:
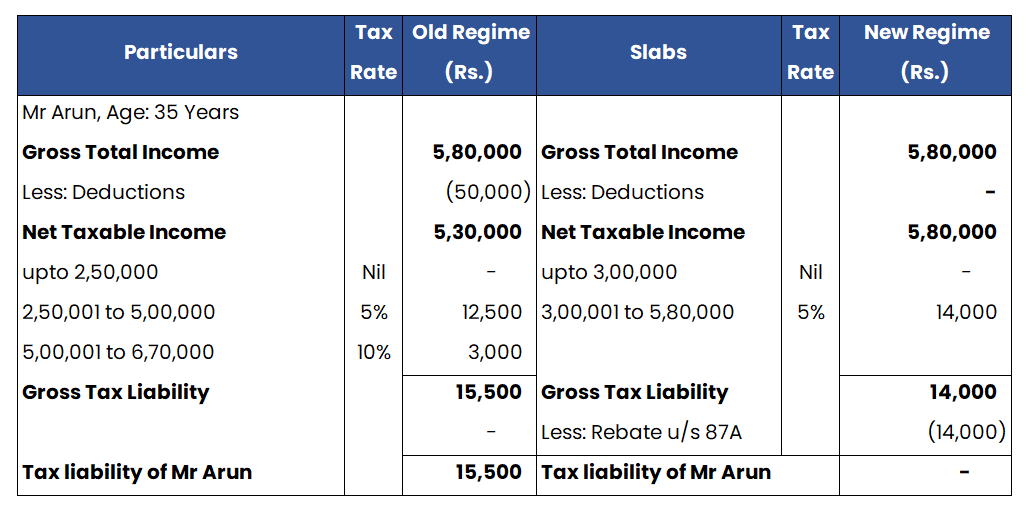
- Mr. Arun’s Age: Being 35 years old, Mr. Arun falls under the general individual category for tax slabs under the Old Regime (basic exemption ₹2.5 Lakhs).
- Old Regime Calculation: Tax is computed step-by-step according to the slabs. No rebate under Section 87A is available because his Gross Total Income (₹5,80,000) exceeds the ₹5,00,000 limit for this rebate in the old regime.
- New Regime Calculation: Tax is computed step-by-step according to the new regime’s slabs, which have a higher initial exemption limit of ₹3,00,000. A full rebate of the tax payable (₹14,000) is allowed under Section 87A in the new regime because his Gross Total Income (₹5,80,000) is within the ₹7,00,000 limit for this rebate.
- Beneficial Regime: The New Tax Regime is more beneficial as it results in zero tax liability due to the enhanced rebate under Section 87A.
Solution
Reasoning for Calculations and Beneficial Regime:
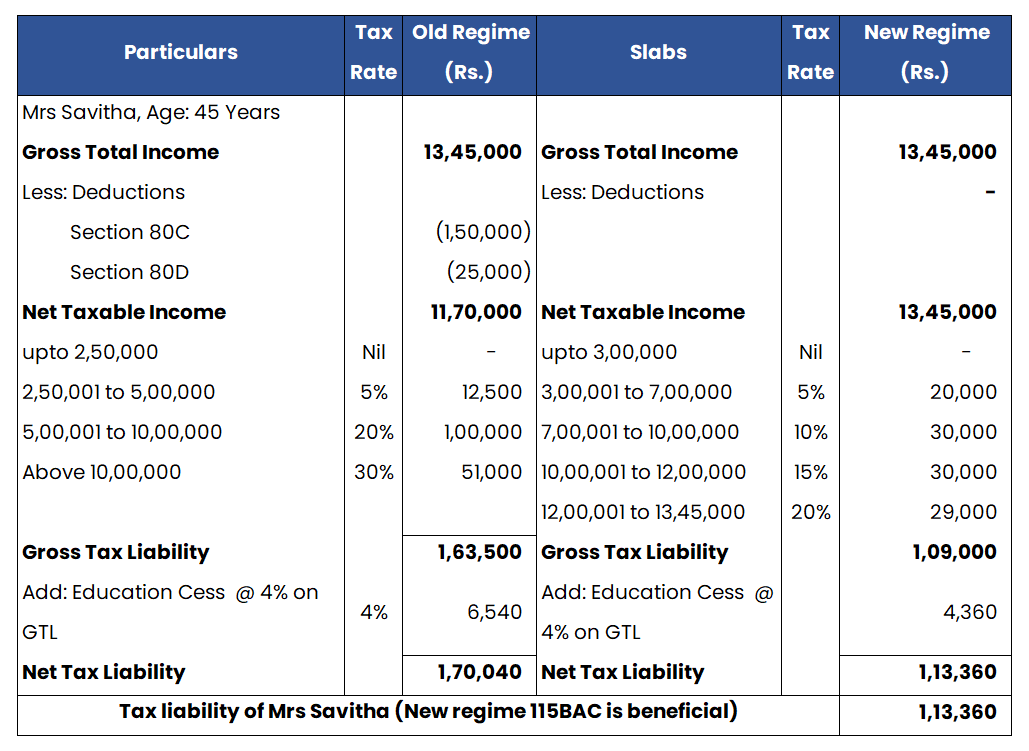
- Ms. Savitha’s Age: As a 45-year-old, Ms. Savitha is a general individual for old regime tax slabs (basic exemption ₹2.5 Lakhs).
- Old Regime Calculation: Tax is computed using the standard slabs. No rebate under Section 87A is available as her Gross Total Income (₹13,45,000) significantly exceeds the ₹5,00,000 limit.
- New Regime Calculation: Tax is computed using the progressive slabs of the new regime. No rebate under Section 87A is available as her Gross Total Income (₹13,45,000) exceeds the ₹7,00,000 limit for this rebate.
- Beneficial Regime: The New Tax Regime is more beneficial because its lower progressive slab rates result in a substantially lower tax liability compared to the old regime for this income level, even without claiming deductions.
Solution
Reasoning for Calculations and Beneficial Regime:
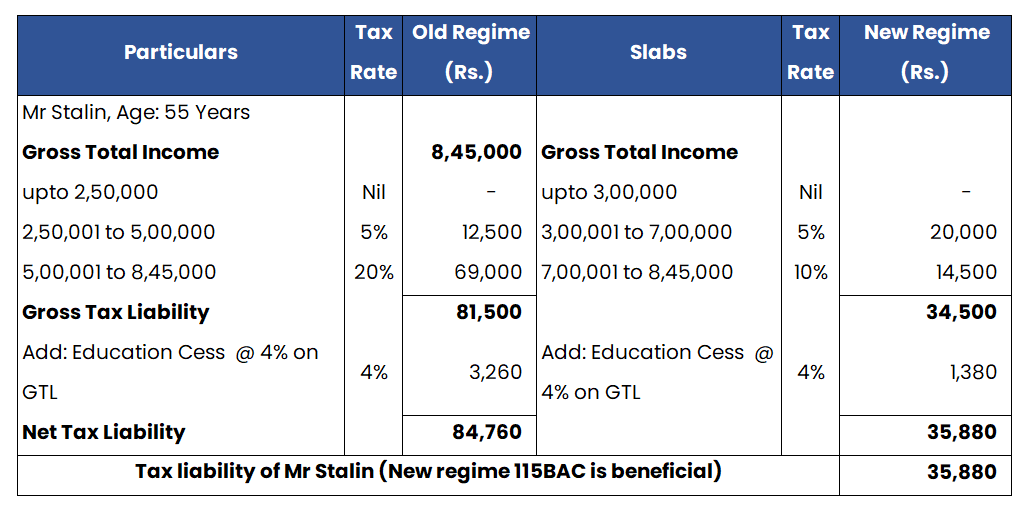
- NRI Status: This is a crucial factor. NRIs are subject to different rules: They are not eligible for the higher basic exemption limits (₹3 Lakhs for senior citizens or ₹5 Lakhs for super senior citizens) under the Old Regime, irrespective of their age. The basic exemption for NRIs is always ₹2,50,000 under the old regime. They are not eligible for rebate under Section 87A in either regime.
- Old Regime Calculation: Tax is computed using the general individual slabs (₹2.5 Lakhs exemption). No rebate is applied.
- New Regime Calculation: Tax is computed using the new regime’s slabs (₹3 Lakhs exemption). No rebate is applied.
- Beneficial Regime: The New Tax Regime is significantly more beneficial for Mr. Stalin, as its lower slab rates (especially for income above ₹7 Lakhs) result in lower tax liability compared to the old regime.