Following information are available:
(a) Cash sales for the year were Rs.10,00,000 and sales on account (Credit Sales) Rs.12,00,000.
(b) Payments on accounts payable for inventory totalled Rs.7,80,000.
(c) Collection against accounts receivable were Rs.7,60,000.
(d) Rent paid in cash Rs.2,20,000, outstanding rent being Rs.20,000.
(e) 4,00,000 Equity shares of Rs.10 par value were issued for Rs.48,00,000.
(f) Equipment was purchased for cash Rs.16,80,000.
(g) Dividend amounting to Rs.10,00,000 was declared, but yet to be paid.
(h) Rs.4,00,000 of dividends declared in the previous year were paid.
(i) An equipment having a book value of Rs.1,60,000 was sold for Rs.2,40,000.
(j) The cash account was increased by Rs.37,20,000.
Solution:
Cash Flow Statement (Direct Method):
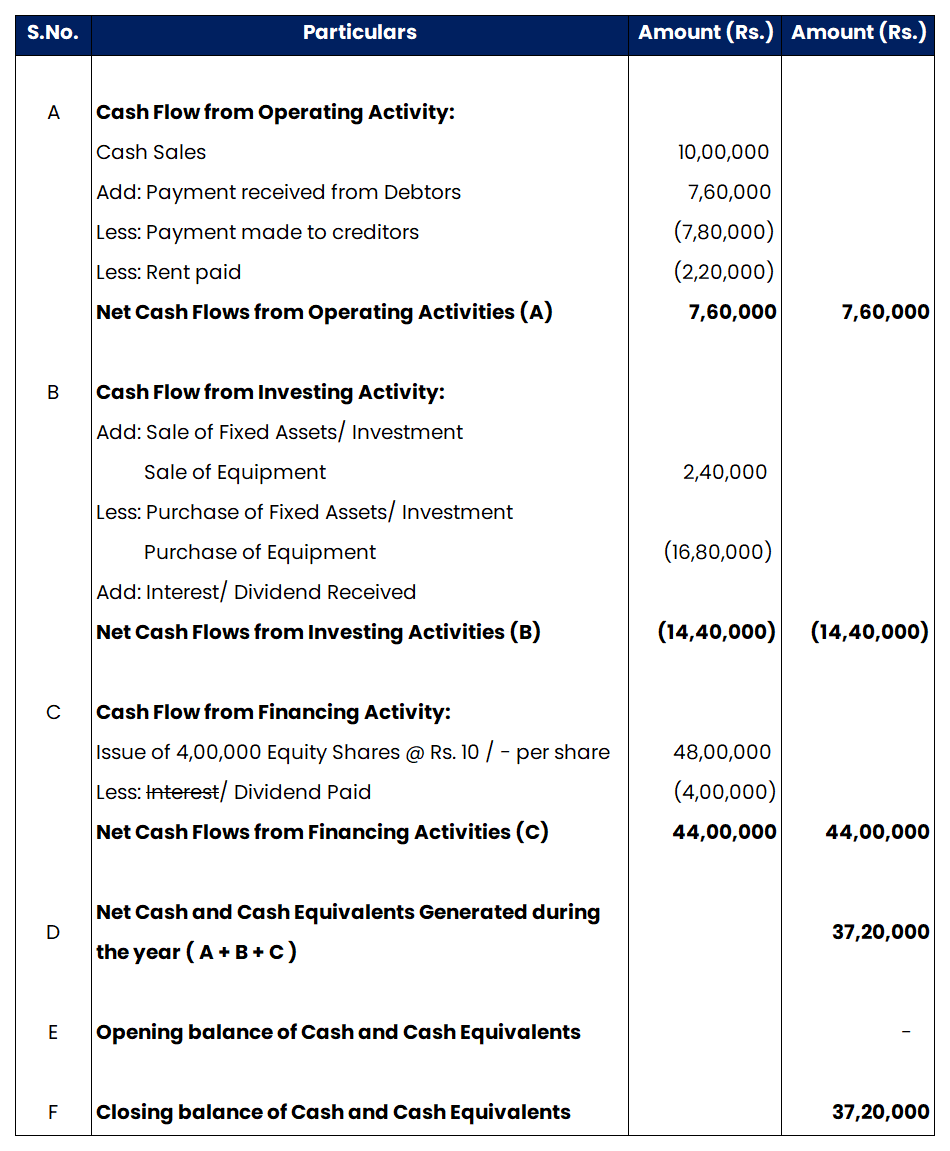
Notes:
1. Dividend declared but not yet paid is not a cash expense because they just declared which does mean they have paid it.
2. Issue of equity shares at par – Since the total cash received (Rs.48,00,000) is different from the value of all the shares issued (4,00,000 shares * Rs.10/share = Rs.40,00,000), the company must have issued the shares at a premium of Rs. 8,00,000 / -. Therefore total cash inflow is Rs.48,00,000 / –