Deductions under House Property:
Under section 24 of the Income Tax Act it is allowed to make following deduction from the Annual Value of House Property;
- Municipal Taxes Paid
- Standard Deduction [Section 24(a)]
- Interest on Borrowed Capital [Section 24(b)]
Municipal Taxes Paid:
Municipal taxes levied by any local authority in respect of house property is allowed as deduction, if:
- Taxes are borne by the owner; and
- Taxes are actually paid by him during the year.
Net Annual Value = Gross Annual Value – Municipal Taxes Paid
For a self-occupied house property, since the Annual Value is Nil, the municipal tax paid shall not be deductible.
Standard Deduction:
A. Standard Deduction of 30% on Net Annual Value
- This 30% deduction is allowed even when actual expenditure on the property is higher or lower.
- Therefore this deduction is irrespective of the actual expenditure one may have incurred on insurance, repairs, electricity, water supply etc.
- For a self-occupied house property, since the Annual Value is Nil, the standard deduction is also zero on such a property.
B. Deduction of Interest on Home Loan for the property:
Section 24, of Income tax Act states that, if any house is acquired, constructed using borrowed capital. Then interest paid on such borrowed capital is eligible for deduction & the amount of deduction is as follows:
Situation 1: When the house is self-occupied:
- If a person has taken a home loan to build/purchase a house for own use then interest paid is eligible for deduction.
- The deduction towards interest is limited to Rs. 2 lakh per financial year for each assessee.
- For example, In FY 2022-23, you took a home loan of Rs.1 crore & paid Rs.5 lakhs as interest in the same year. As per Sec 24, only Rs.2 lakhs will be allowed as interest deduction & this will be set-off from other head income as house property loss. Balance interest paid of Rs.3 lakhs cannot be claimed as deduction by the assessee.
Deduction for interest paid or payable on borrowed capital shall be allowed in respect of two self-occupied house properties. However, the aggregate amount of deduction under this provision shall remain same i.e., Rs. 2 Lakh.
Generally in case of self-occupied house, the annual value is NIL. Therefore, any municipal taxes paid will not be allowed & standard deduction will also be NIL. The only amount which will be allowed as deduction shall be Interest on borrowed capital which will be limited to Rs.2 Lakhs.
This will generate a loss under house property head which can be set-off from other heads income or Income from Salary.
Situation 2: Interest on borrowed funds when the house is let-out:
- The treatment of let-out property is different from self-occupied. In this case, the Gross Annual Value needs to be determined as discussed earlier.
- The additional benefit of renting out the property is that one can carry forward extra loss. For example, Income from House property is Rs. 3 Lakhs and interest paid is Rs.5 lakhs u/s 24. Out of this, only to the extent of income from house property will be allowed as deduction in one Financial year i.e., Rs.3 Lakhs, however the asseesee in his return can carry forward excess interest of Rs. 2 Lakhs for next 8 AY’s. While in case of self-occupied property, this loss will lapse.
Pre-Construction Interest:
Pre-Construction Interest = Interest charged by the banker on housing loan starting from loan Sanction date till earlier of following;
- Date of repayment of loan or
- 31st March immediately prior to the date of completion of the construction/ acquisition of the property.
Conditions for claiming Pre-construction interest :
- The deduction for this interest is allowed in 5 equal installments starting from the year in which the house is purchased or the construction is completed.
- Is allowed when you have taken a loan for purchase or construction of a house property (not allowed in case of the loan for repairs or reconstruction).
- For example, if construction of property completed in FY 2024-25, on 25th June 2024, assessee can claim 1/5th of interest paid up till 31st March 2024 when they file return for FY 2025-25.
- Though pre construction interest is allowed to be deducted on the basis of 1/5th each year beginning the year in which the construction is completed – the total amount of pre-construction interest and interest on housing loan that can be claimed in a year should not exceed Rs 2 lakhs in case of Self occupied property and in case of Let out property it can be carried forward to next 8 AY’s.
Interest on borrowed capital table (Maximum Limit) :
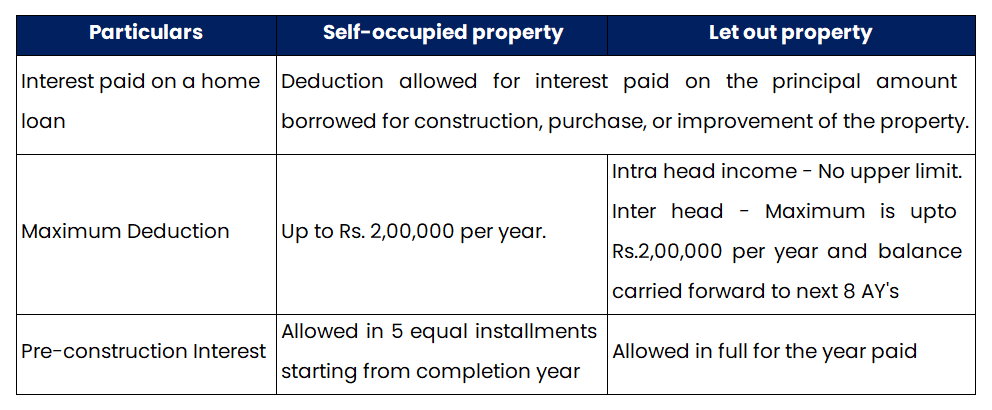
No limit on deduction: Unlike self-occupied properties where the interest deduction is capped at Rs. 2 lakhs, there’s no upper limit on the interest we can deduct for a let-out property. This means we can deduct the entire amount of interest paid on the home loan against their rental income.
Deduction capped by income: However, this deduction is restricted to the extent of our income from the house property. In simpler terms, we can’t deduct more interest than the rental income we receive.
Tax regime: This deduction applies under both the old and new tax regimes in India.
Excess interest: If the interest amount exceeds our rental income, we can carry forward the unutilized deduction for up to eight subsequent financial years and claim it against future rental income.
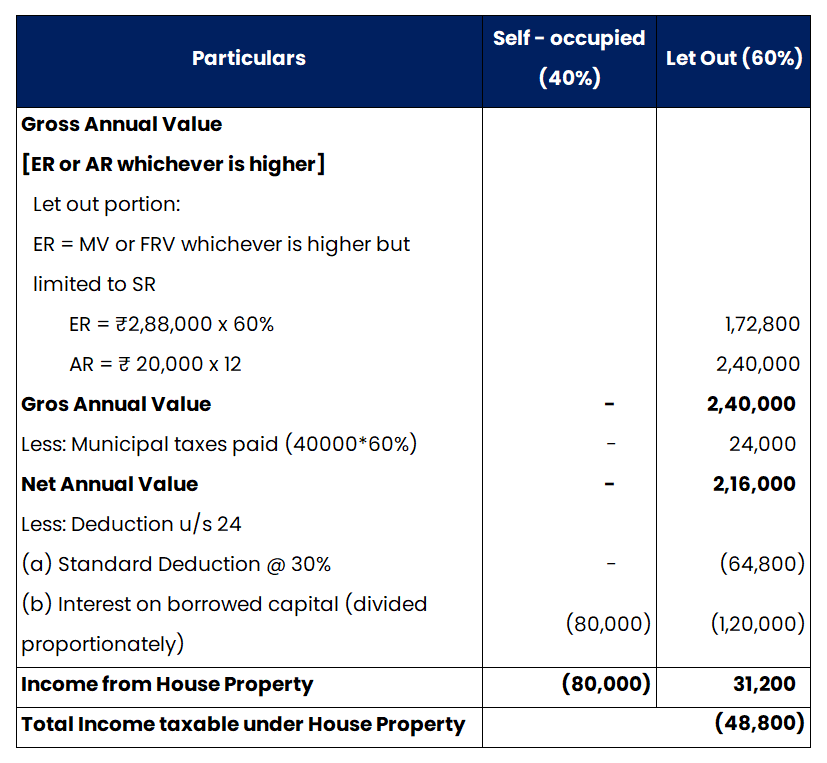
Computation of Income Under the head House Property:
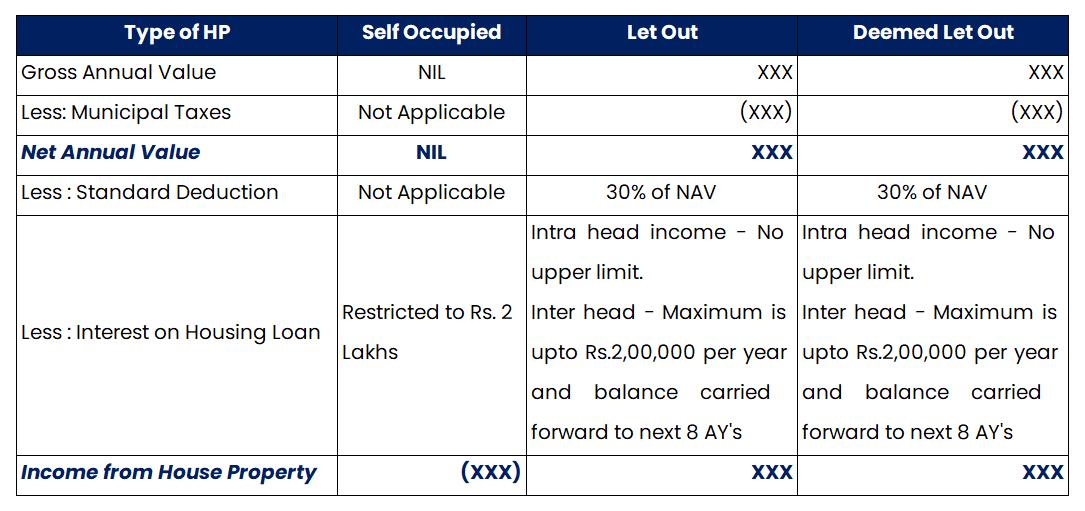
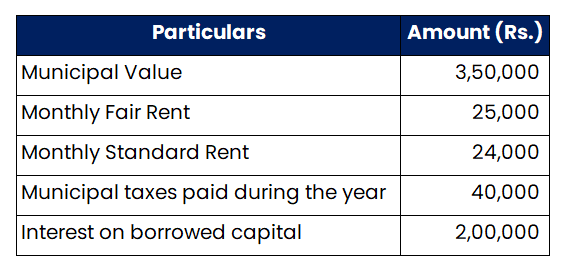
Computation of income from house property
Property owned by co-owners:
- For the purpose of computing income from house property, the annual value of the property will be taken in proportion to their share in the property.
- In such a case, each co-owner shall be entitled to claim benefit of self-occupied house property in respect of their share in the property.
- Where the shares of co-owners are not definite, the income of the property shall be assessed as that of an Association of persons.