Other Deductions:
- Deduction in Respect of Contribution to certain Pension Funds (Sec 80CCC)
- Deduction in Respect of Contribution to Pension Scheme of CG (Sec 80CCD)
- Loan for Higher Studies (Sec 80E)
- Deduction for Rent paid (80GG)
Deduction in Respect of Contribution to certain Pension Funds (Sec 80CCC):
- Deduction can be claimed in respect of payment of premium for annuity plan of LIC or any other Insurer is provided.
- The Premium must be deposited to keep a contract for annuity plan of LIC or any other insurer in force, such that pension can be received from the fund.
- Interest or Bonus accrued or credited to the assessee’s A/c shall not be reckoned as Contribution.
- The Maximum Deduction allowed is Rs.1.5 lakh.
Deduction in Respect of Contribution to Pension Scheme of CG (Sec 80CCD):
Pension Scheme of Central Government:
- It is mandatory for persons entering the service of the Central Government on or after 1st January, 2004, to contribute 10% of their salary every month towards their pension account.
- A matching contribution is required to be made by the Government to the said account. The benefit of this scheme is also available to individuals employed by any other employer as well as to self-employed individuals.
Deduction: Section 80CCD provides deduction in respect of contribution made to the pension scheme notified by the Central Government. Accordingly, the Central Government has notified the ‘Atal Pension Yojana (APY)’ as a pension scheme, contribution to which would qualify for deduction under section 80CCD in the hands of the individual.
Quantum of deduction:
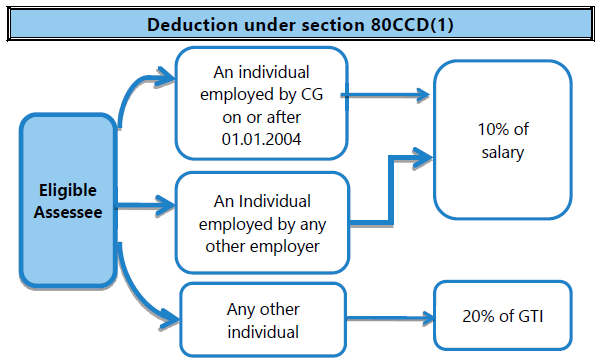
- Section 80CCD(1) provides a deduction for the amount paid or deposited by an employee in his pension account subject to a maximum of 10% of his salary.
- The deduction in the case of a self-employed individual would be restricted to 20% of his gross total income in the previous year.
- Section 80CCD(1B) provides for an additional deduction of up to Rs. 50,000 in respect of the whole of the amount paid or deposited by an individual assessee under NPS in the previous year, whether or not any deduction is allowed u/s 80CCD(1).
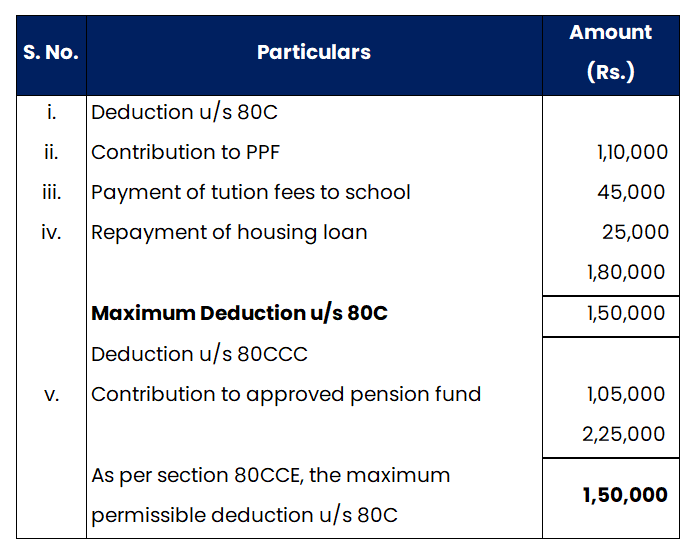
- Whereas the deduction under section 80CCD(1) is subject to the overall limit of Rs. 1.50 lakh under section 80CCE (i.e., the maximum permissible deduction under sections 80C, 80CCC and 80CCD(1) put together), the deduction of upto Rs. 50,000 under section 80CCD(1B) is in addition to the overall limit of Rs. 1.50 lakh provided under section 80CCE.
Contribution towards NPS by Employer [80CCD (2)]:
- Contribution by the employer to NPS is deductible under section 80CCD(2) in the hands of the concerned employee in the year in which contribution is made.
- However, no deduction is available in respect of employer’s contribution which is in excess of 14% or 10% percent of the salary of the Central Govt. employee or any other employee.
- And deduction is available only to salaried employees and not self-employed.
- Salary for this purpose means basic salary + dearness allowance
It shall be noted that full contribution made by the employer is included in the salary of the employee and then deduction is allowed only upto 10%/14% of salary.
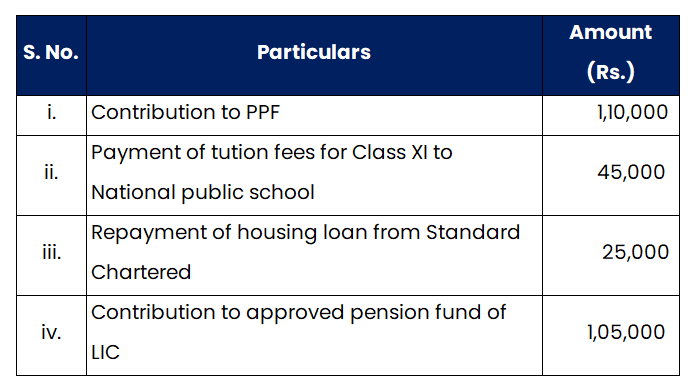
Compute the eligible deduction under Chapter VI-A for the A.Y.2025-26
Solution:
Computation of deduction under Chapter VI-A for the A.Y.2024-25:
Loan for Higher Studies (Sec 80E):
- Tax deduction can be claimed u/s 80E for the interest paid towards education Loan taken for higher studies (after completing Senior Secondary Exam).
- This loan should have been taken for higher education of assesse, spouse or children or for a student for whom assessee is legal guardian.
- Principal Repayment of educational loan cannot be claimed as tax deduction.
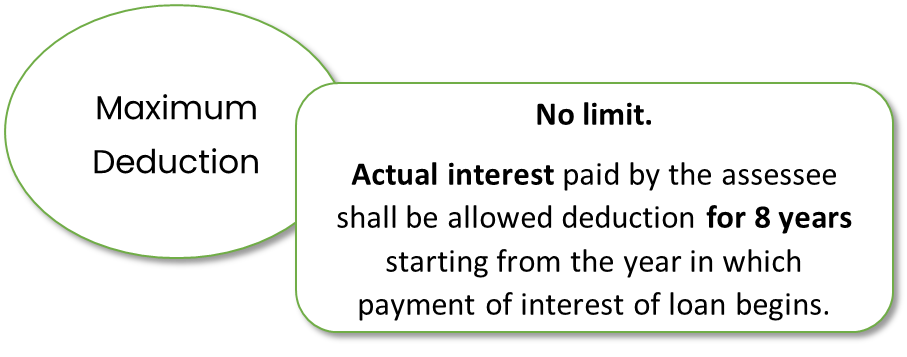
- There is no limit on the amount of interest you can claim as deduction under section 80E. The deduction is available for a maximum of 8 years or till the interest is paid, whichever is earlier.
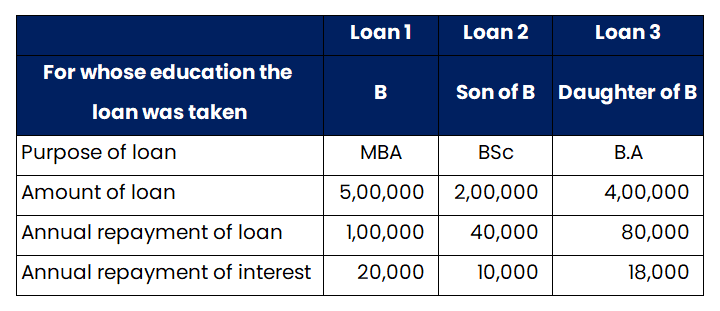
Compute the amount deductible under section 80E for the A.Y.2025-26 if Mr. B has exercised the option of shifting out of the default tax regime provided under section 115BAC(1A).
Solution:
Deduction under section 80E is available to an individual assessee exercising the option of shifting out of the default tax regime provided under section 115BAC(1A), in respect of any interest paid by him in the previous year in respect of loan taken for pursuing his higher education or higher education of his spouse or children.
Higher education means any course of study pursued after senior secondary examination. Therefore, interest repayment in respect of all the above loans would be eligible for deduction.
Deduction under section 80E = Rs. 20,000 + Rs. 10,000 + Rs. 18,000 = Rs. 48,000.
Deduction for Rent paid (80GG):
The Tax Deduction amount under 80GG is Rs.60,000 per annum. Section 80GG is applicable for all those individuals who do not own a residential house & do not receive HRA (House Rent Allowance).
The extent of tax deduction will be limited to the least amount of the following:
- Rent paid minus 10 percent the adjusted total income.
- Rs.5,000 per month.
- 25 % of the total adjusted income.