Case Study 2
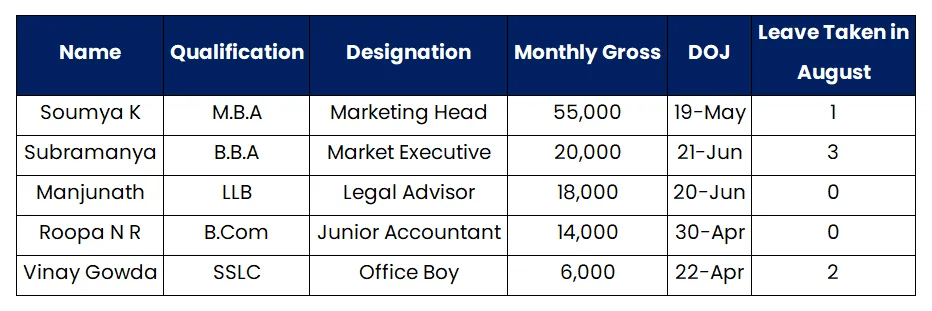
FINC Mines Private Limited has started business during the year and hired employees with following salary and other details:
Note:
- Employee codes format: FINC 101
- Company assumes standard 30 working days in all months.
- Assume Company has taken PT, PF and ESI registration. Assume PT Rs.200, applicable for Soumya, Subramanya and Manjunath only. PF is capped at Rs.1,800/-.
- Employees are eligible for gratuity of 15 days salary per annum. Only for the purpose of calculation of gratuity, number of days in a month to be taken as 26 days.
- Salary Structure (% of Gross): Basic – 40%; HRA – 16%; Conveyance – 6%; Medical – 5%; Spl. Allowance – 33%.
- Marketing team members are eligible for the variable pay at 10% on CTC upon achieving target and 20% on above target.
- TDS deductible for Soumya K is Rs.1,710 per month, while for others it’s Zero.
- Manjunath has taken loan of Rs.50,000 from company and monthly deductible amount is Rs.1,500
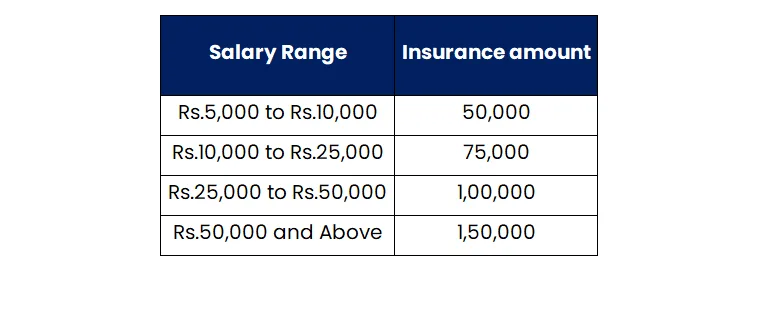
- Company also provides medical insurance to all employees as per following table:
Salary statement for the month of August:
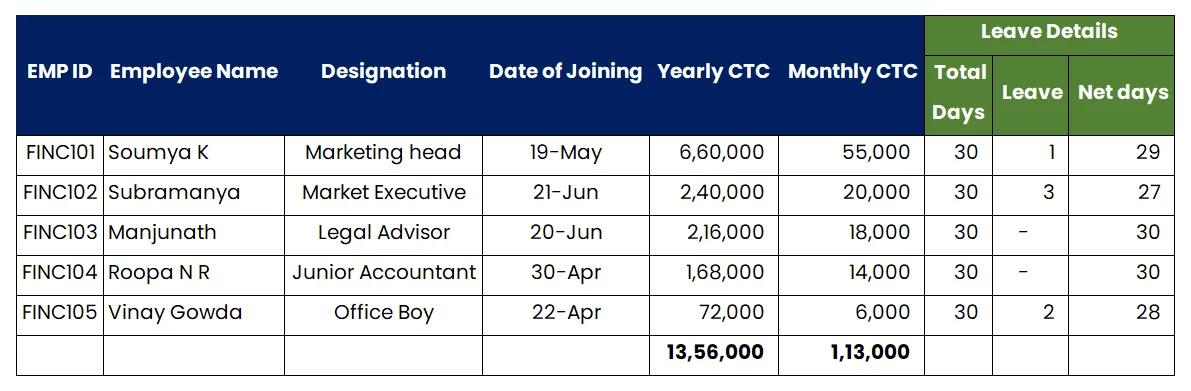
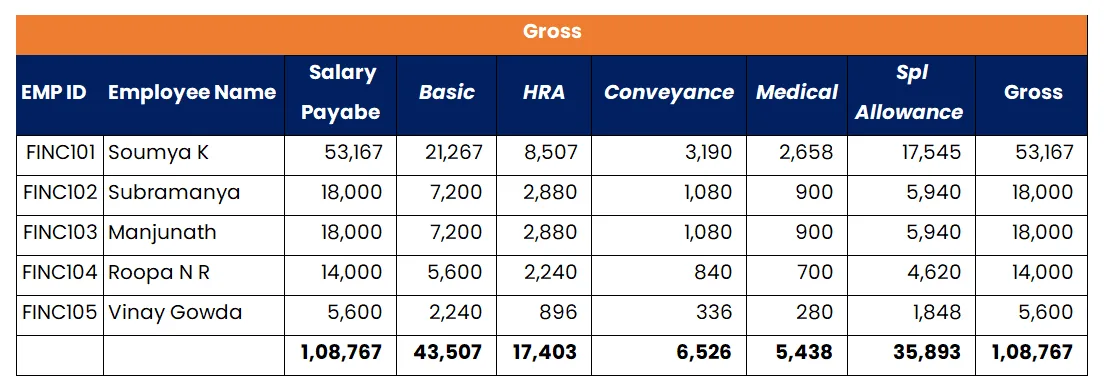
Salary payable has been calculated by dividing Monthly CTC by 30 and multiplying with Net days present after adjusting the leave. Thereafter, the salary structure has been broken down in the given ratio.
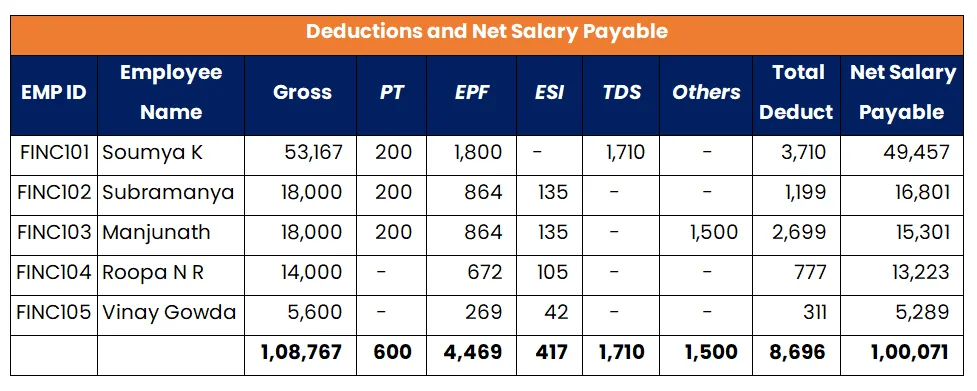
- EPF is 18% of Basic salary subject to maximum of Rs.1,800.
- ESI is 0.75% of of Gross salary if Gross salary is less than Rs.21,000
- Manjunath’s loan deduction of Rs.1,500 has been adjusted.
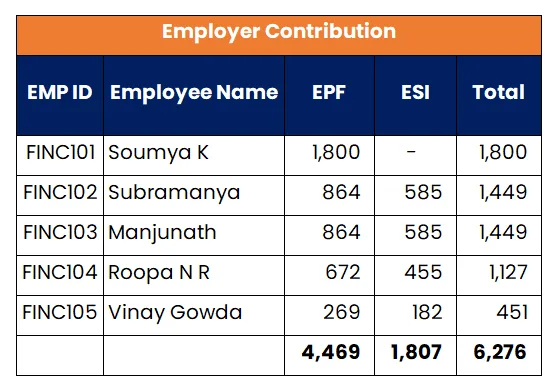
Employer Contribution and Gratuity:
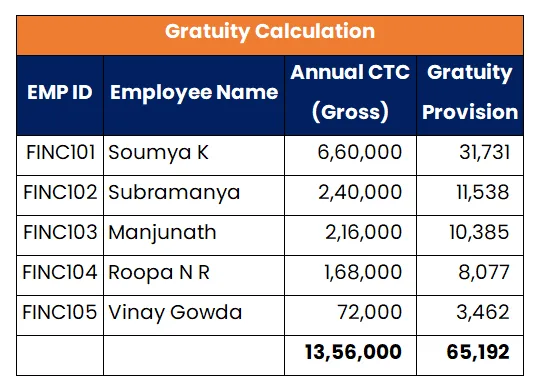
Gratuity has been calculated as follows:
Annual CTC x 15 days / 26 days / 12 months.
E.g. 6,60,000 x 15 / 26 / 12 = 31,731.
As per IT Law, gratuity is calculated as half month salary for 1 full year. However, one month is considered as 26 days in a month.
The company will make a provision of Gratuity expenses Rs.65,192 in their books. Gratuity is mostly payable when the employee exits the organization.
Pay Slips for August:
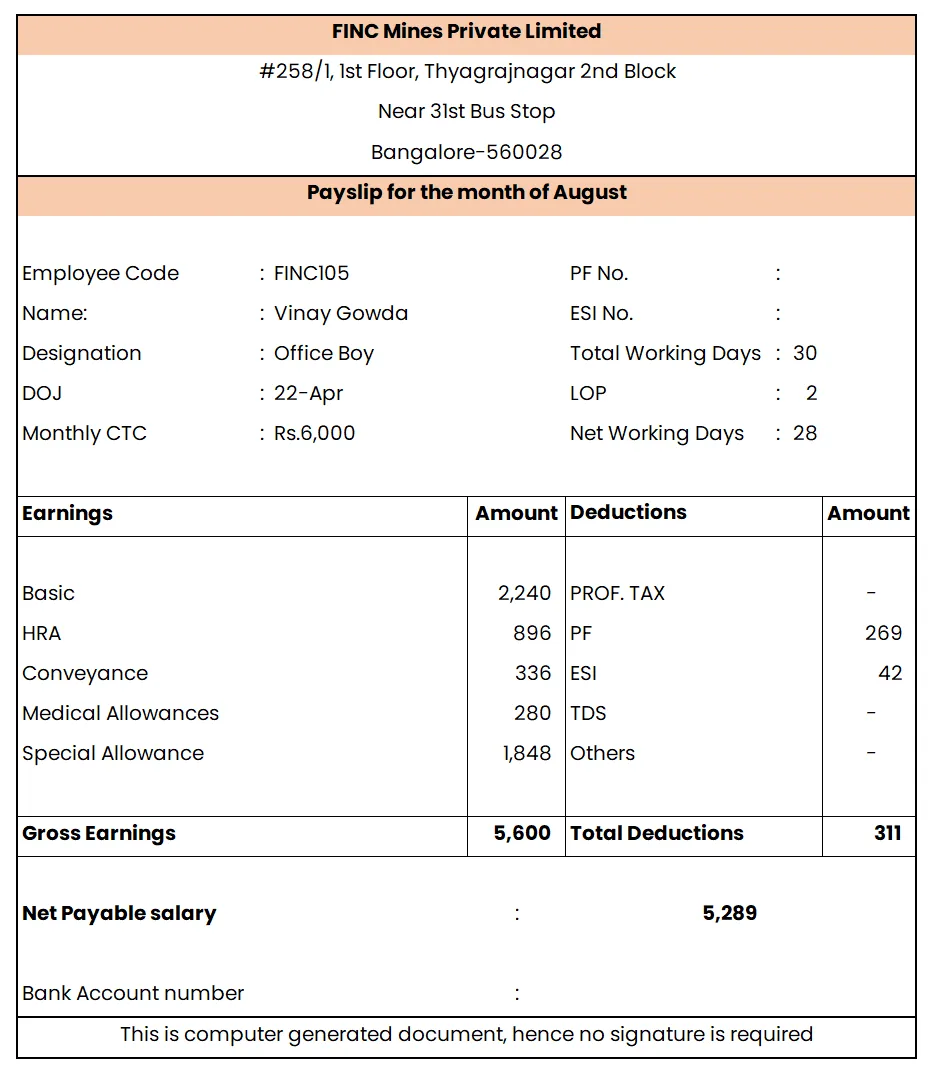
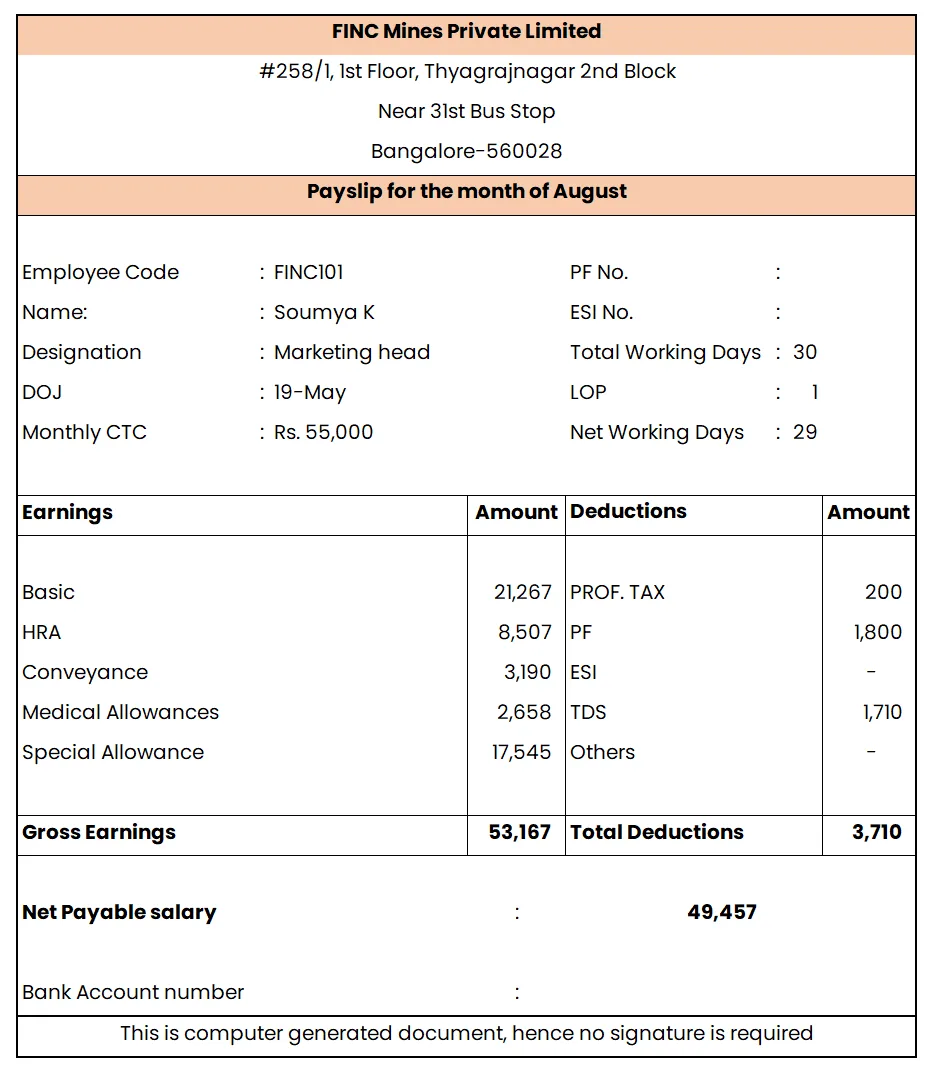
Employee: FINC101
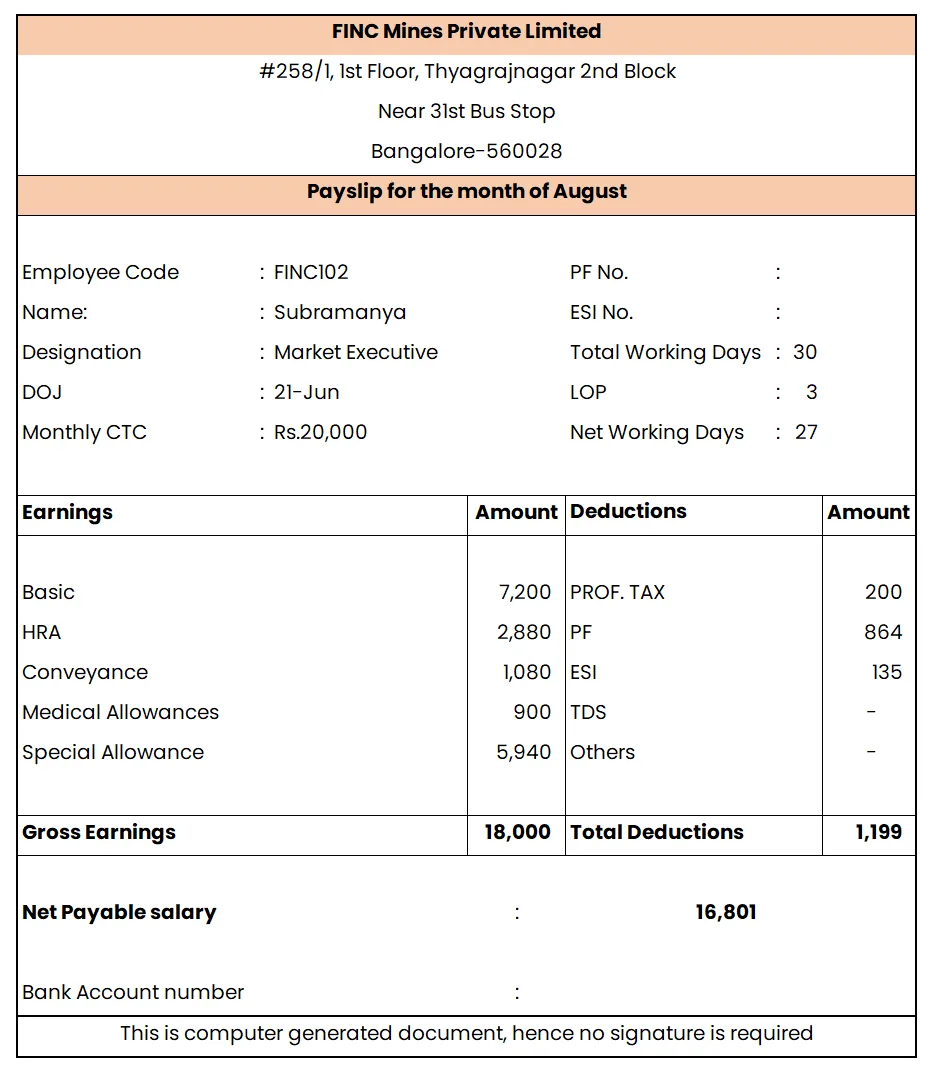
Employee: FINC102
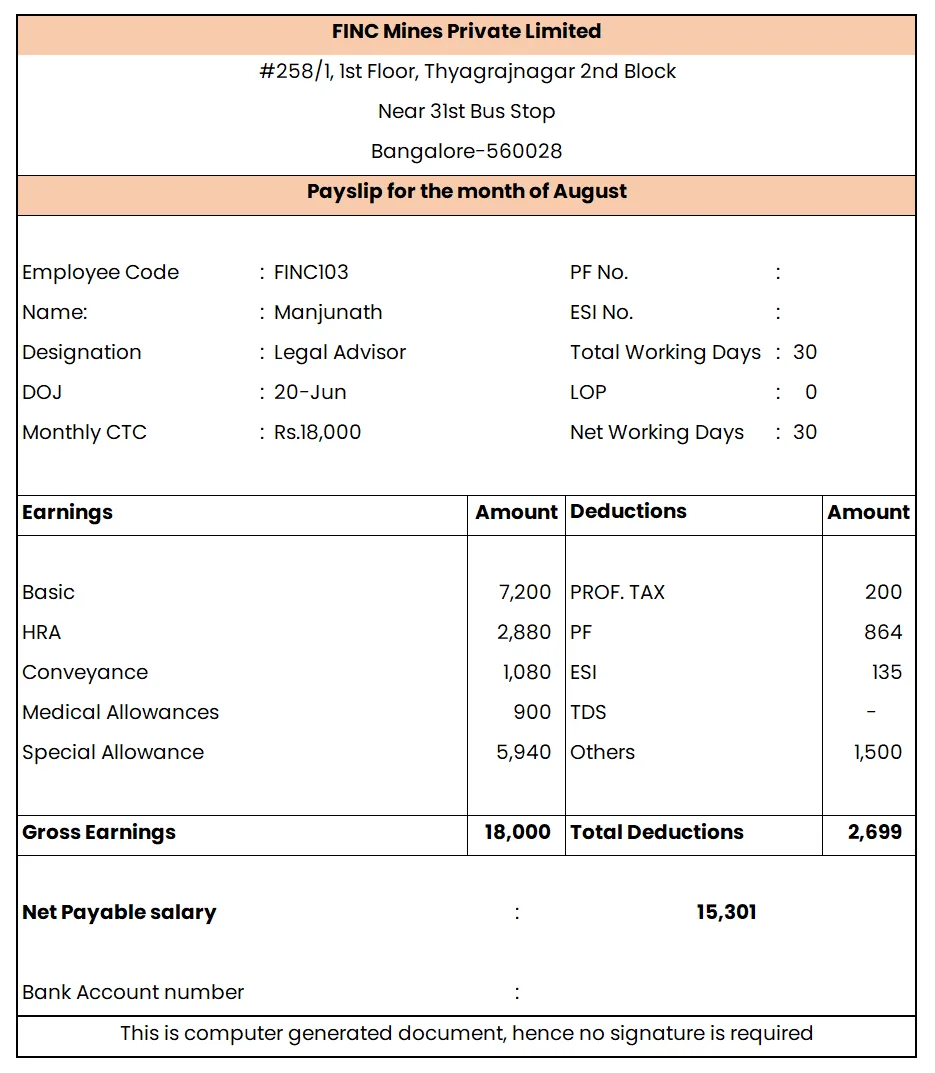
Employee: FINC103
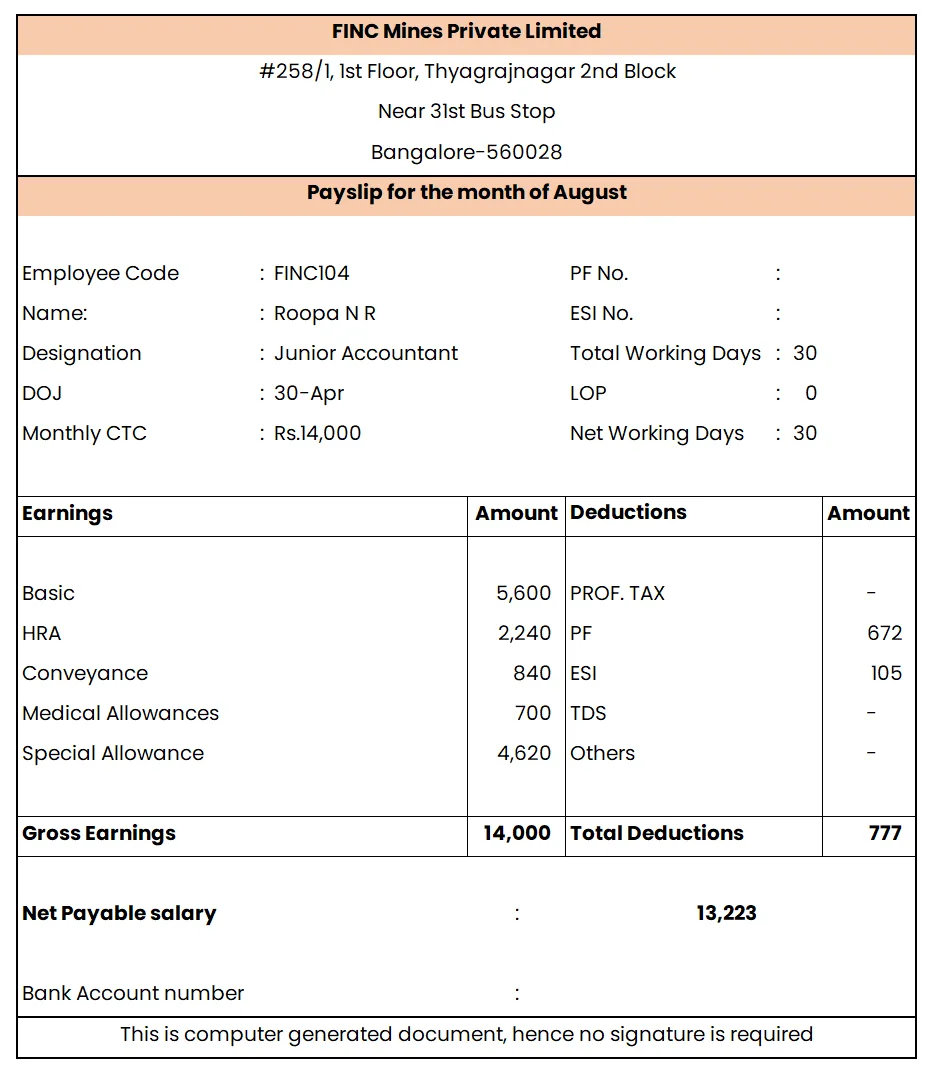
Employee: FINC104
Employee: FINC105