Format of Financial Statement
The financial statements generally include two statements: balance sheet and statement of profit and loss which are required for external reporting and also for internal needs of the management like planning, decision-making and control. Apart from these, there is also a need to know about movements of funds and changes in the financial position of the company. For this purpose, a cash flow statement is prepard.
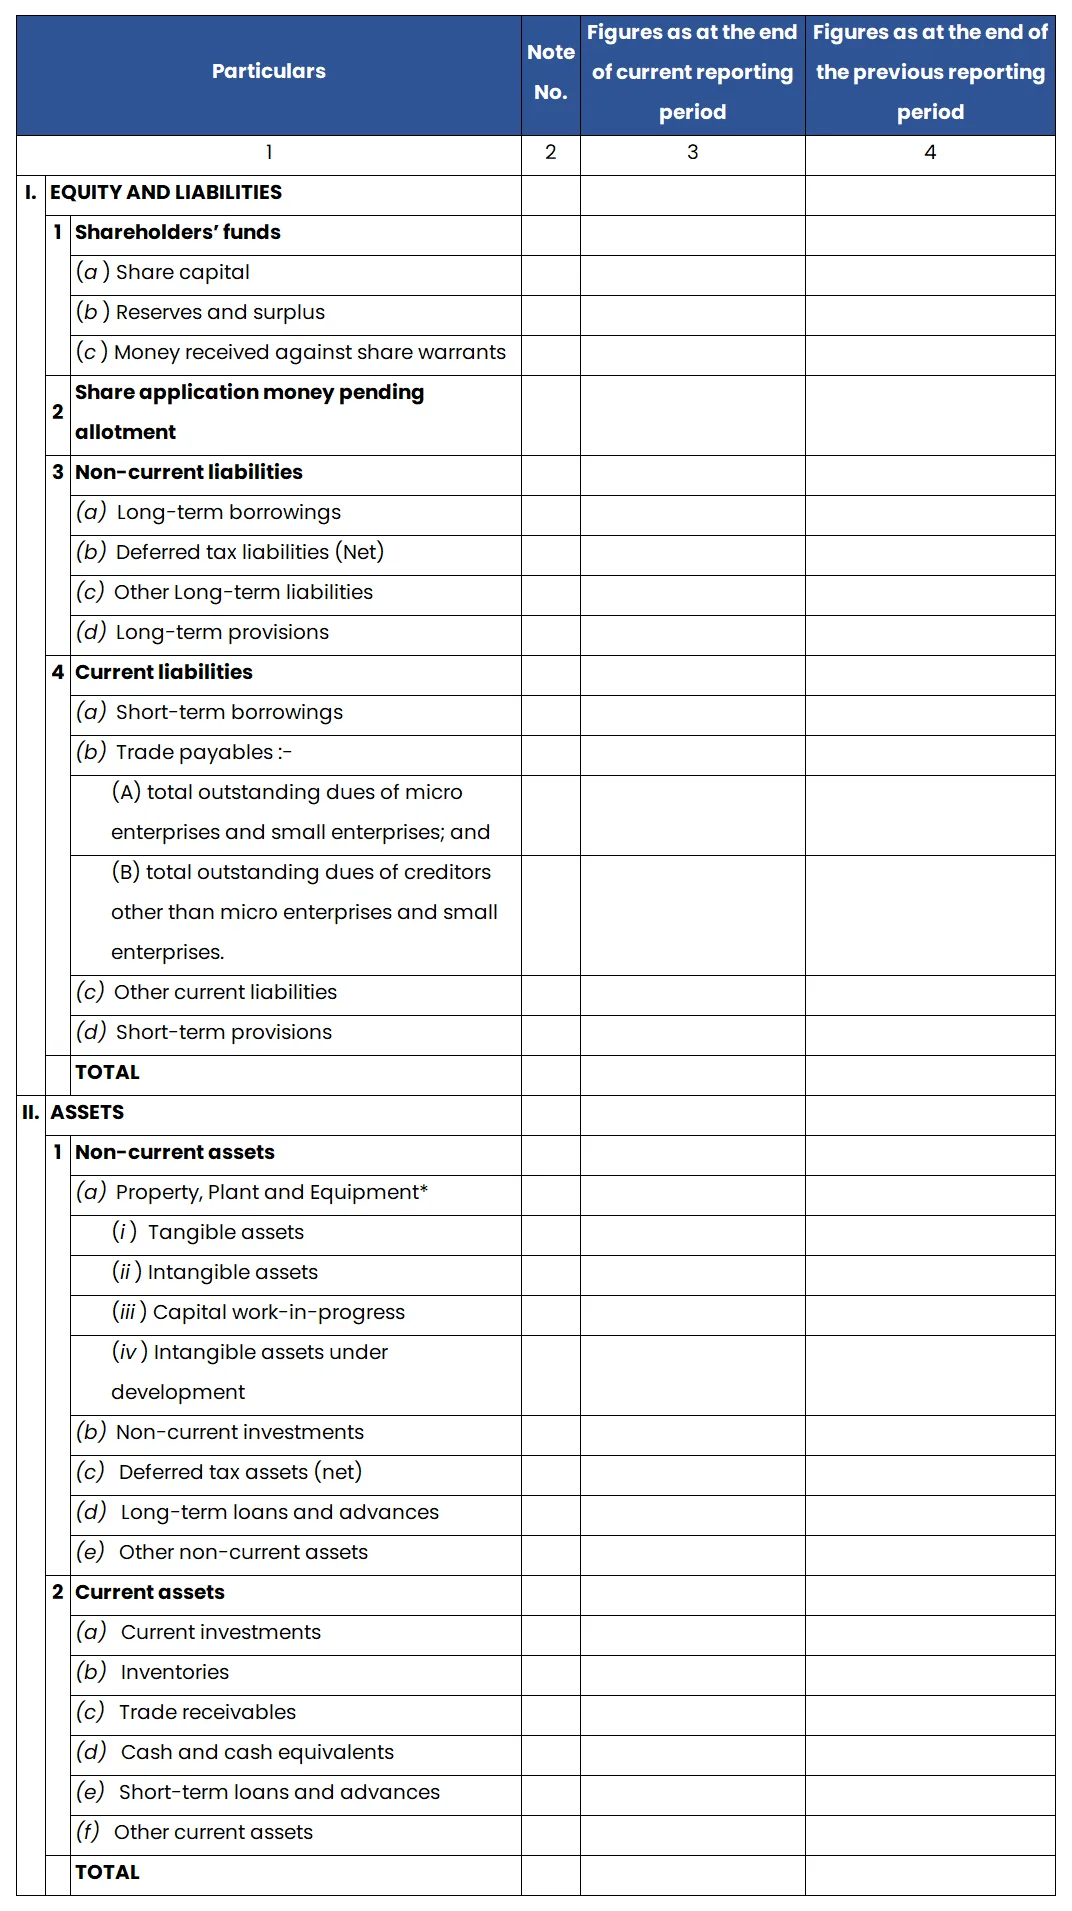
Every company registered under The Companies Act 2013 shall prepare its balance sheet, statement of profit and loss and notes to account thereto in accordance with the manner prescribed in the revised Schedule III to the Companies Act, 2013 to harmonise the disclosure requirement with the accounting standards and to converge with new reforms.
Traditionally, financial statements were drawn based on own requirements, however, once a Company is formed, it has to follow the format as per Schedule III of the Companies Act 2013. The differences are given below:
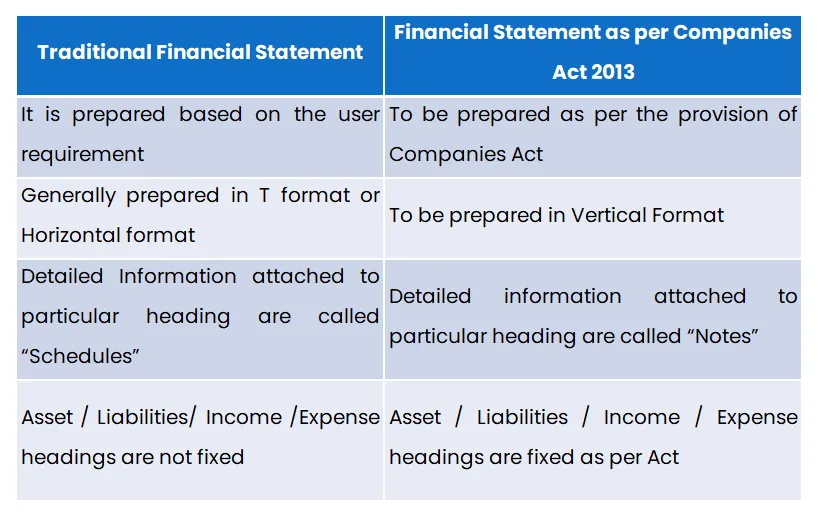
Various formats are given below:
Balance Sheet:
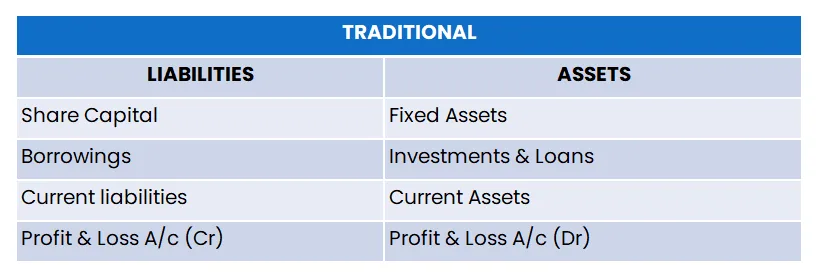
The Total of Liabilities side and Assets side should match.
Schedule III Financial Statement:
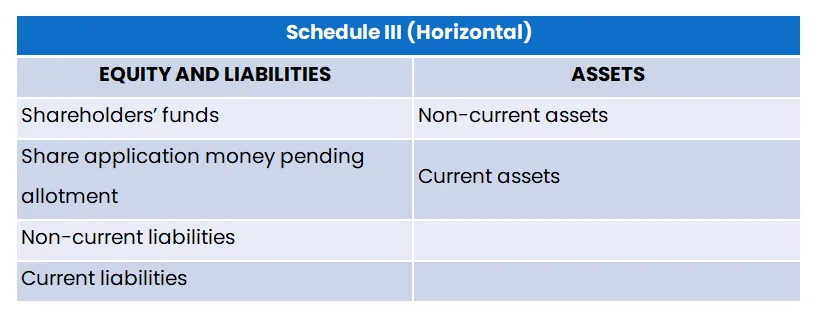
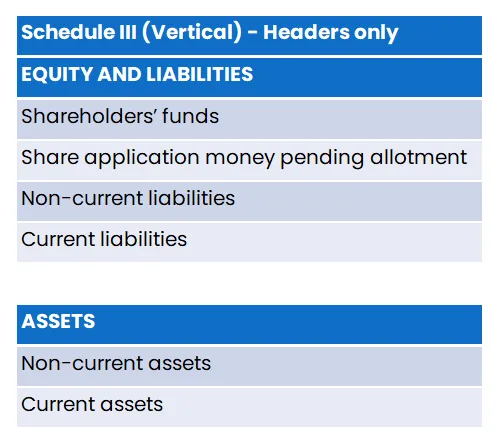
Balance Sheet as per Schedule III (Detailed):
Profit & Loss Account
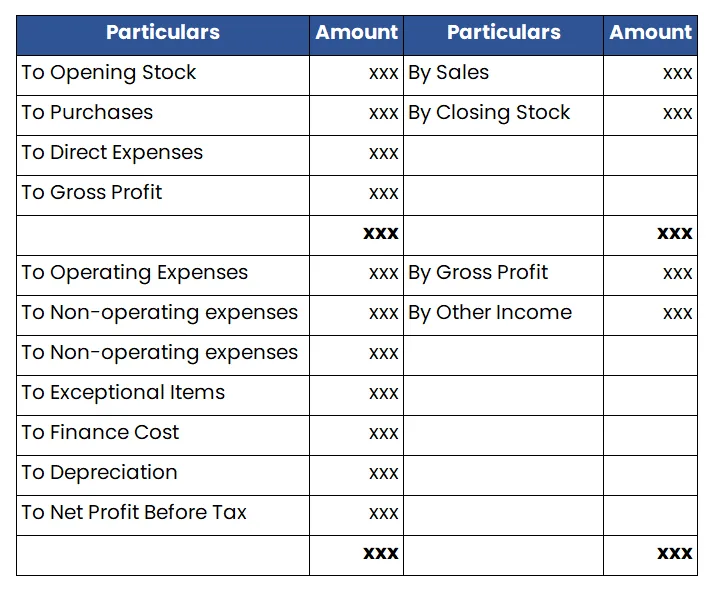
Traditional Profit & Loss A/c:
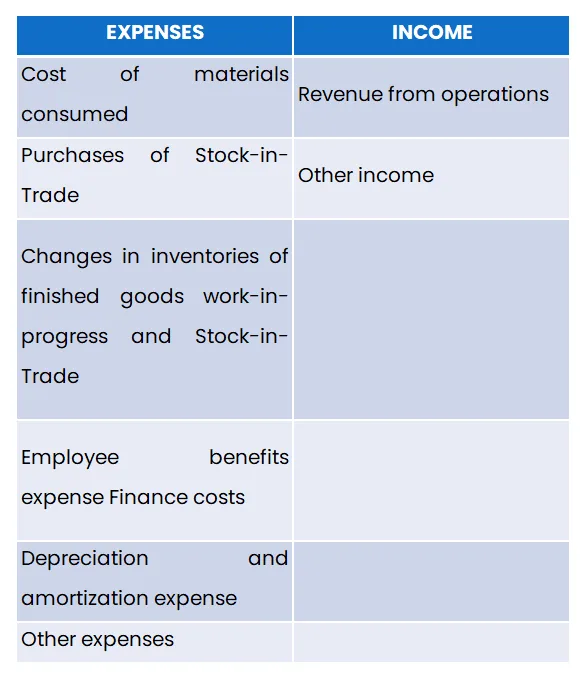
Statement of Profit & Loss as per Schedule III (Horizontal):
Statement of Profit & Loss (Vertical):
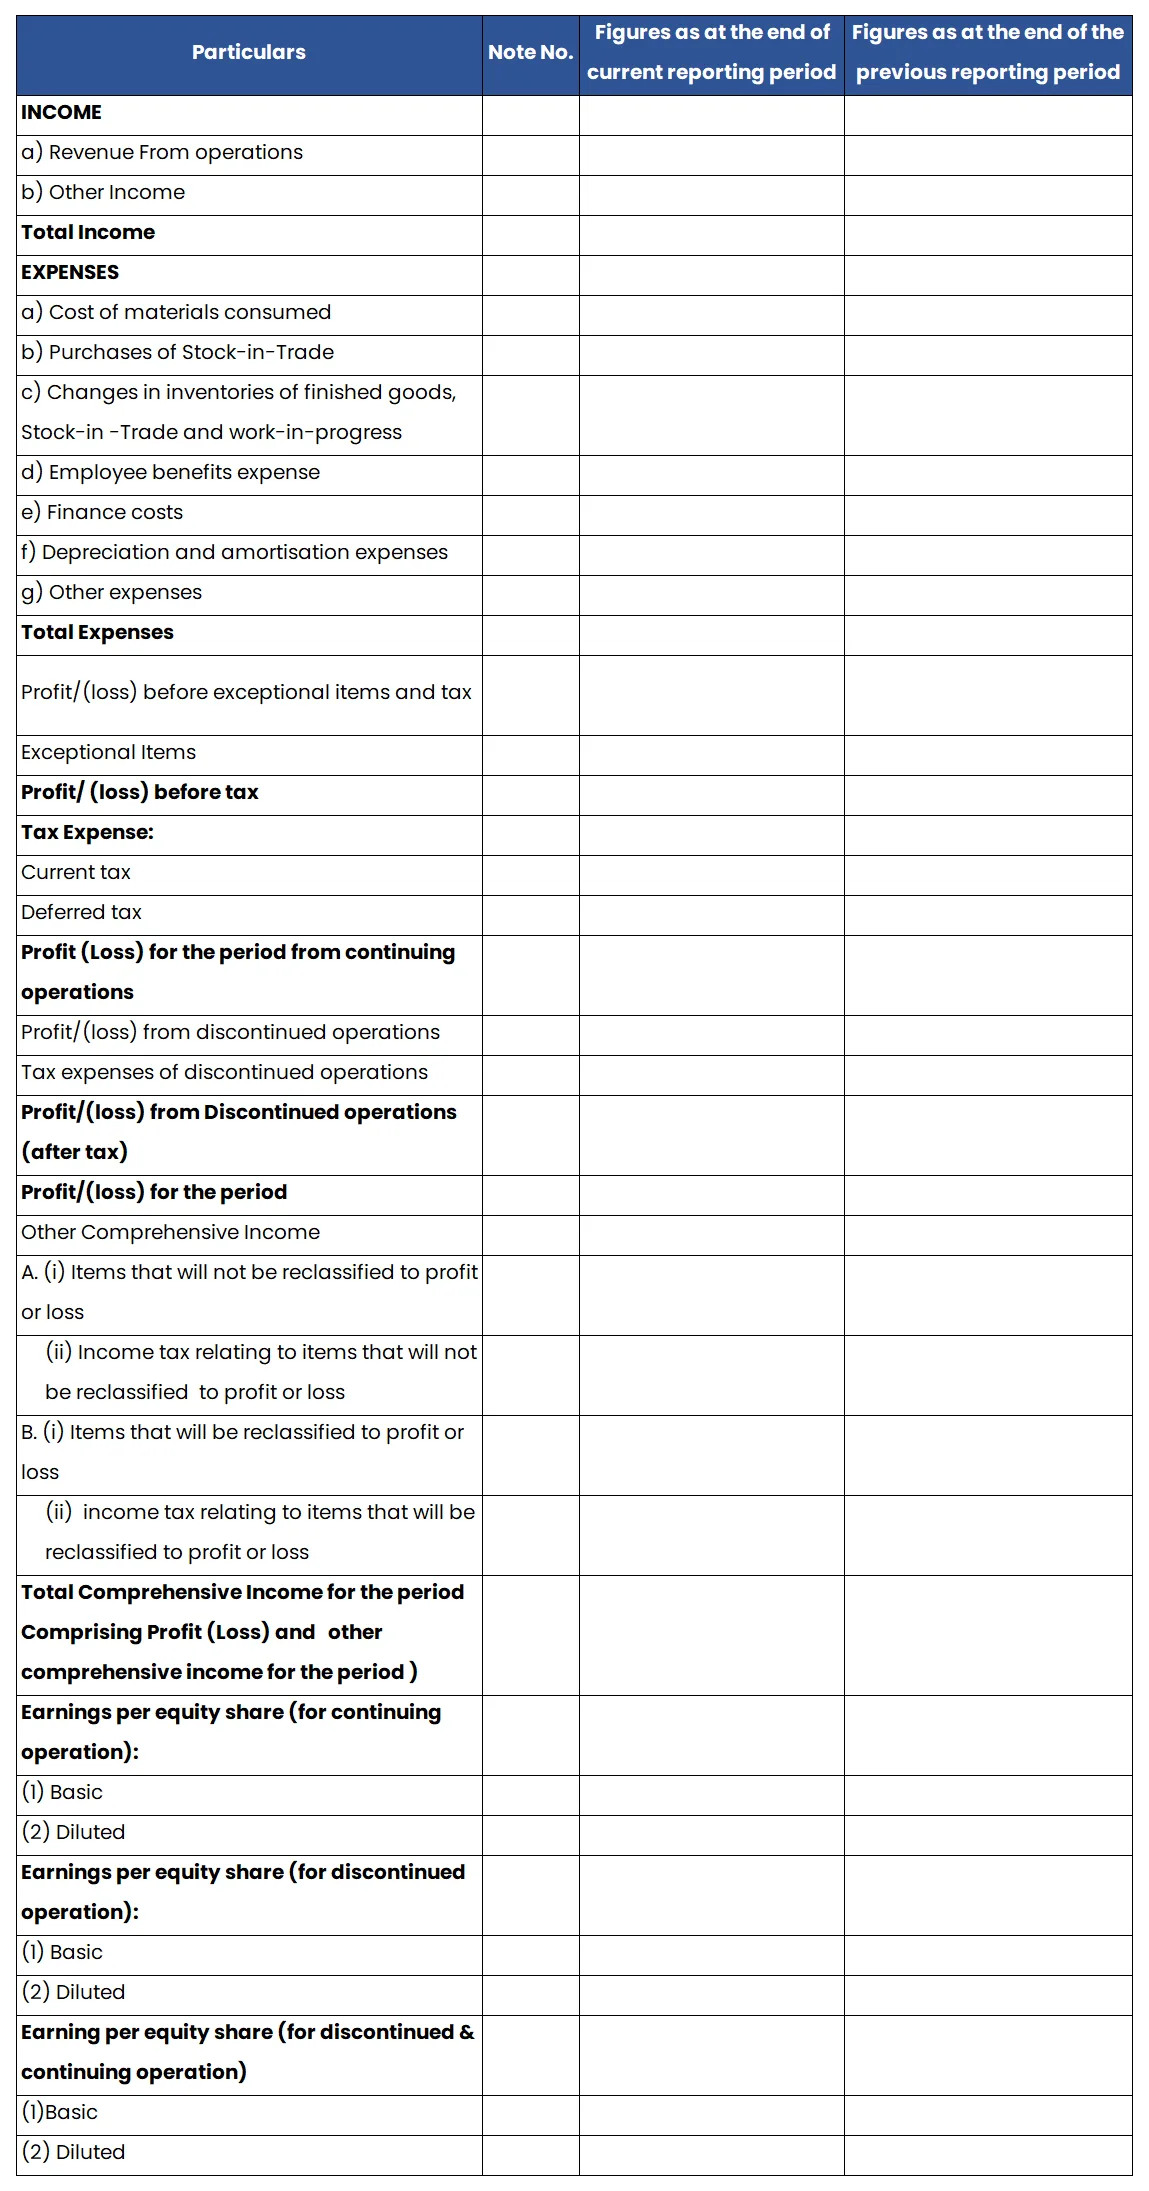
Please note that there is no concept of Gross Profit under Companies Act format.