Advance Tax:
Advance tax means income tax paid in advance instead of lump sum payment at the year end. These payments have to be made in installments as per due dates provided by the Income Tax Act.
Generally, tax on the income earned in the previous year is paid in the respective assessment year, but in certain cases, an assessee may be required to pay tax during the previous year itself, as Advance tax.
- The scheme of advance tax is based on the concept “Pay as you earn”.
- Under this scheme assessee needs to estimate its income and tax liability of the previous year and pay tax on basis of such estimation in the previous year itself.
- For instance, income earned during the previous year 2024-25 is normally taxable in the assessment year 2025-26, however under the scheme of Advance tax, assessee is required to pay tax on estimated income of previous year 2024-25 in the previous year itself.
Who should pay Advance Tax?
As per section 208 of the Income Tax Act 1961, every person whose estimated tax liability for the year after reducing TDS is more than or equal to Rs. 10,000 is liable to pay advance tax.
- Where the advance tax liability of the assessee is ₹ 10,000 or more, the assessee should pay such tax in the previous year itself within the due date
Applicable to all assessee irrespective of his residential status and citizenship
Who is exempted from paying Advance-tax?
- Senior citizens who are above the age of 60 years, not having any income from business or profession are excluded from paying advance tax.
- Others having tax liability of less than Rs 10,000/- after considering TDS and tax relief on income.
Difference between Advance Tax & Self-Assessment Tax
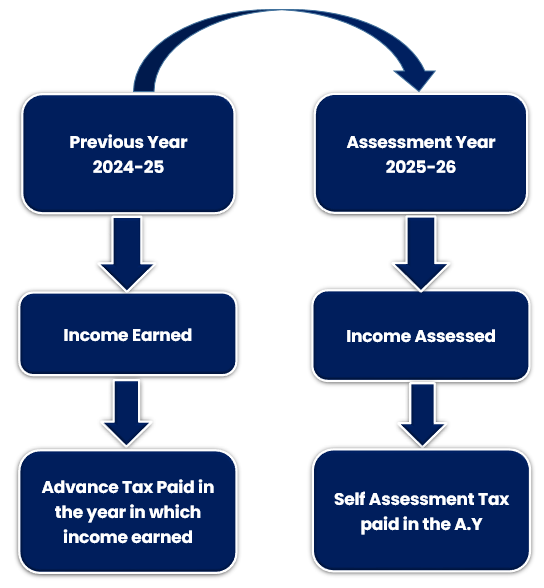
- The difference is between Advance Tax and Self-Assessment Tax is that both are Income tax with the difference of the time of payment.
- Advance tax is paid on the estimation of the Income earned during the year and is paid before the end of the Financial Year i.e. 31st March.
- Self-Assessment Tax is the tax paid as per the Assessment of income made at the time of filing the return. So it is paid in the Assessment Year before filing the Income Tax Return.
Due date for Advance Tax
Advance tax due dates for corporate and non-corporate assessee

Note – Any amount paid by way of advance tax on or before 31st March shall also be treated as advance tax paid during each financial year ending on 31st March.