Steps to Compute Advance Tax of Individual
- An assessee has to estimate his current income and pay advance tax thereon. He need not submit any estimate or statement of income to the income tax department.
- Where an obligation to pay advance tax has arisen, the assessee shall himself compute the advance tax payable on his current income at the rates in force in the financial year and deposit the same, whether or not he has been earlier assessed to tax.
- The tax calculated shall be reduced by the amount of tax deductible at source.
Step 1: Compute Annual Estimated Income
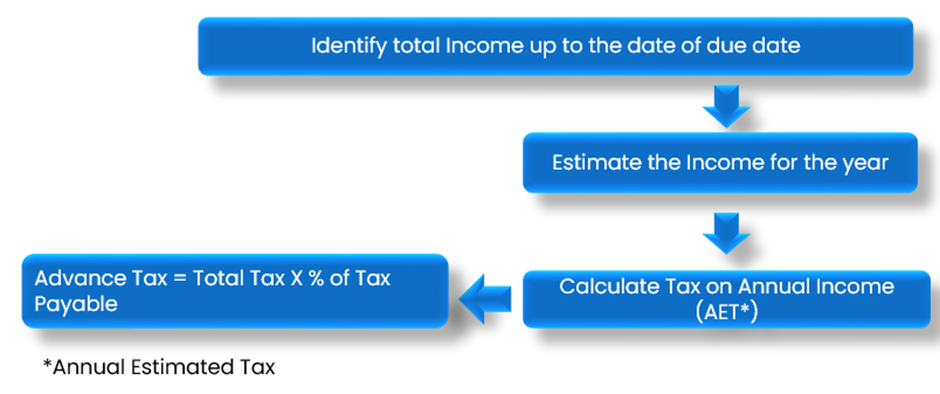
Step 2: Calculate Advance Tax on Annual Estimated Tax (AET)
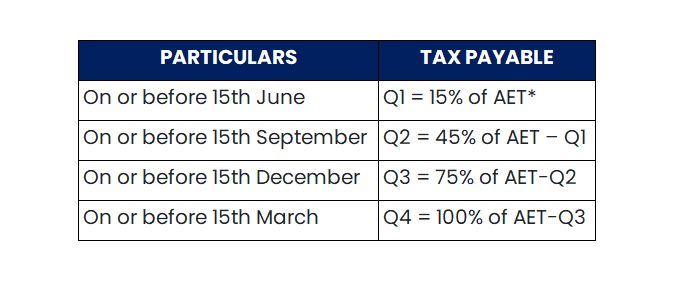
*Annual Estimated Tax
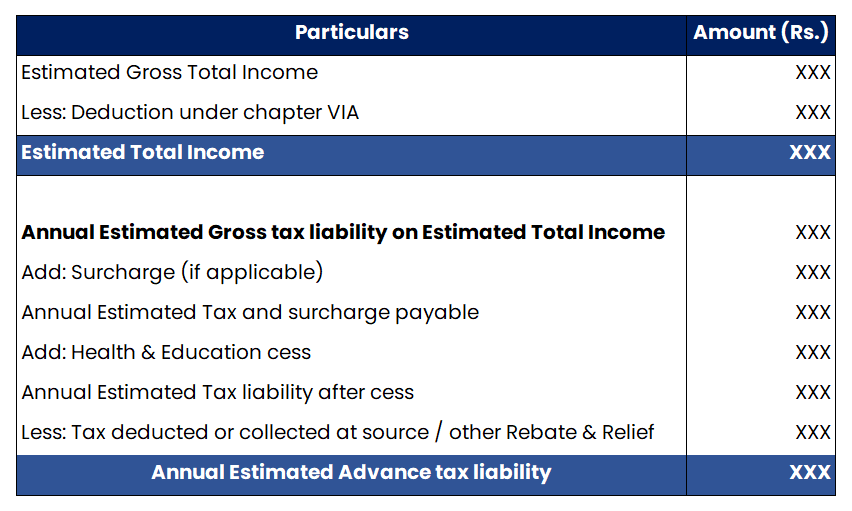
Statement of Annual Estimated Advance Tax liability
Interest on non-payment of advance tax:
Where an assessee fails to pay advance tax or defers the payment of advance tax on specified date, he shall be liable to pay interest u/s 234B & 234C.
Interest for non-payment or short-payment of advance tax [Section 234B]
Interest for default in payment of advance tax is levied at 1% per month or part of a month. This interest is chargeable from 1st April of the Assessment Year. As per provisions of section 234B, interest will be applicable/ payable only under the following two situations:
- The taxpayer is liable to pay advance tax. However, he fails to pay the same; or
- The taxpayer has paid the advance tax. However, the amount paid is less than 90% of the assessed tax.
Let us understand how 234B Interest is calculated with the help of examples:
When no tax deduction at source is made during the calculation of the tax and the amount is more than Rs. 10,000, the individual defaults to pay the advance tax.
Interest Calculation:
- Number of months for which interest to be calculated – April 25 to June 25
- Rs 48,000 x 1% x 3months = Rs 1,440/-
- Mr. A is liable to pay Rs 1,440/- interest as per section 234B along with tax liability Rs.48,000/-
When the total tax to be paid after Tax Deduction at Source is more than Rs. 10,000, the individual defaults to pay the advance tax.
Interest Calculation:
- The interest calculation will be 40000-20000(advance tax)= Rs. 20,000
- Interest= 20000*1%*4 =Rs. 800
- Thus, Anagha is liable to pay interest of Rs 800 under section 234B.
If the advance tax is paid by the taxpayer but not complete. If the taxpayer pays less than 90% of the assessed tax, he or she is liable to pay interest for the months delayed.
Interest Calculation:
- Amount on which interest is to be calculated = 63000-30000(advance tax)= Rs.33,000
- Interest = 33,000*1%*3 = Rs.990.
- So, Vishnu pays Rs. 990 as interest under Section 234B.
Interest payable for deferment of Advance Tax installments (Section 234C):
Section 234C provides for levy of interest for default in payment of instalment(s) of advance tax. In other words, Interest is levied if advance tax paid in any instalment(s) is less than the required amount.
Rate of interest:
Interest under section 234C for default in payment of instalment(s) of advance tax is charged at 1% per month or part of a month.
Period of levy of interest:
Interest under section 234C is levied for a period of 3 months, in case of short fall in payment of 1st, 2nd and 3rd instalment and for 1 month, in case of short fall in payment of last instalment.
Calculation Of Interest Under Section 234C:
Interest under section 234C is levied on the short paid amount of instalment(s) of advance tax.
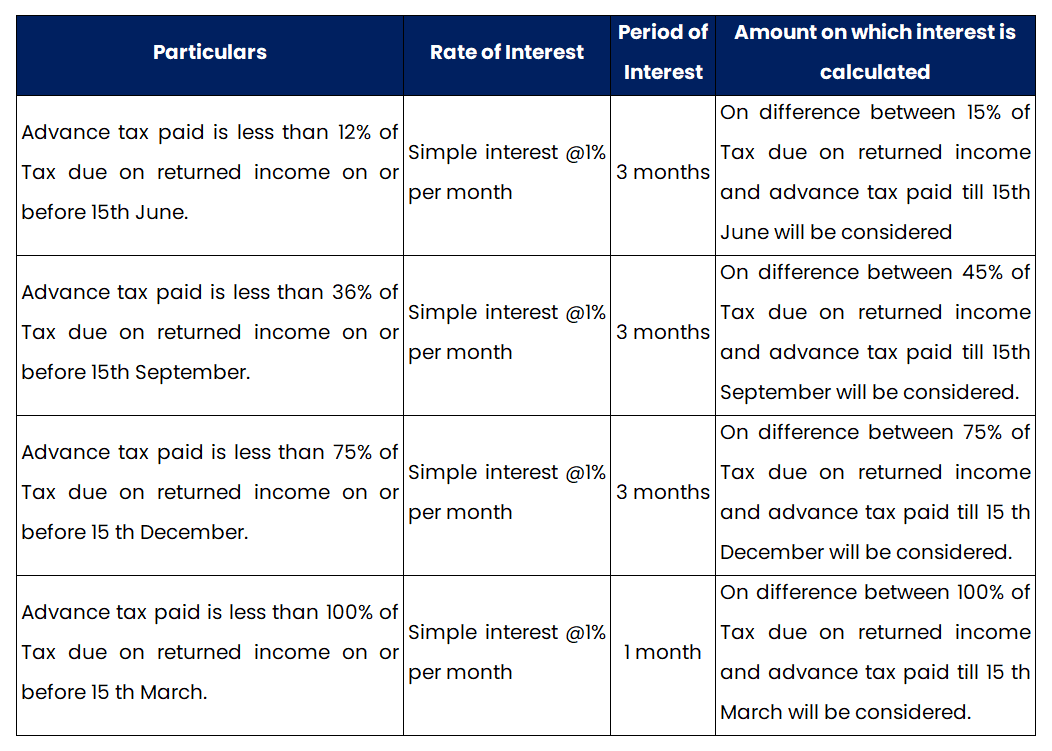
Example to understand how interest under section 234C is calculated if the Estimated Advance tax liability is Rs.1,00,000 for the year
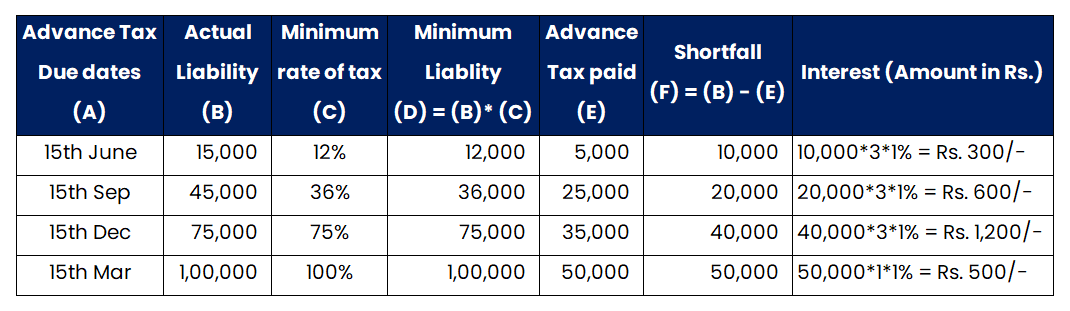
The total interest payable is Rs 2,600/-.