Form 122, Form 124 and Form 125
For the purpose of computing TDS on salary, the employer may require certain information from the employee relating to salary received from another employer, other income, deductions, exemptions, investments and other eligible claims.
Under the Income-tax Act, 2025 and Income-tax Rules, 2026, the forms applicable for furnishing such information have been revised.
The important forms relating to salary TDS are:
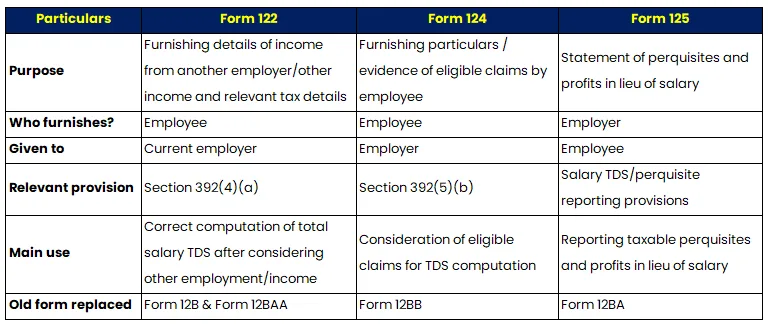
- Form No. 122 (Ealier Form 12B) – Furnishing of details of income by an employee to the current employer.
- Form No. 124 (Ealier Form 12BB) – Statement of claims by an employee for deduction of tax.
- Form No. 125 (Ealier Form 12BA) – Statement of particulars of perquisites, other fringe benefits or amenities and profits in lieu of salary.
Form 122
Furnishing of details of income by an employee
Under Section 392(4)(a) of the Income-tax Act, 2025, an employee may furnish details of income to the current employer for the purpose of computing TDS on salary.
Form No. 122 is relevant where an employee has received salary from another employer or has other income/loss that is required to be considered for TDS computation.
When is Form 122 applicable?
An employee may furnish Form No. 122 where the employee has:
- Changed employment during the same Tax Year;
- Received salary from another employer during the same Tax Year;
- Income under any other head of income;
- Loss under the head Income from House Property; or
- Tax deducted or collected during the Tax Year.
The information enables the current employer to determine the employee’s estimated total income and deduct the appropriate amount of TDS under Section 392(1).
Information that may be furnished in Form No. 122
1. Personal Information:
Name of the employee, PAN (Permanent Account Number), and address.
2. Previous Employer Details:
Details of the previous employer, such as Permanent Account Number (PAN) and Tax Account Number (TAN) and Period of Employment.
3. Salary Details:
Breakdown of the previous salary in detail that includes basic salary, dearness allowance (DA), leave travel allowance (LTA), house rent allowance, prerequisites, leave encashment, etc.
4. Tax Deducted:
Details of TDS deducted by the previous employer during the relevant Tax Year.
5. Other Income and Loss:
Details of income under other heads and eligible loss under the head Income from House Property, as applicable.
Form 124:
Statement of Claims by an Employee for Deduction of Tax
Form No. 124 is the form to be used by an employee for furnishing particulars of eligible claims to the employer for the purpose of computing TDS on salary.
It is prescribed under the Income-tax Rules, 2026 in connection with Section 392 of the Income-tax Act, 2025.
The employee shall furnish the following evidence or the particulars specified in the Table below:
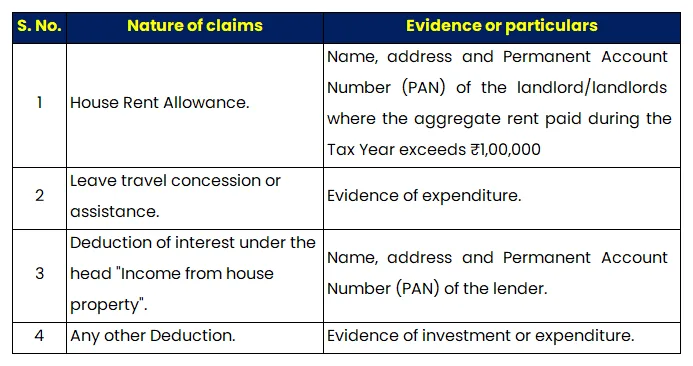
Key details that may be included in Form 124:
The prescribed form contains relevant information such as:
1. House Rent Allowance
Where the employee claims HRA exemption, relevant particulars of:
- Rent paid;
- Period of occupation;
- Landlord’s name;
- Landlord’s address; and
- Landlord’s PAN, wherever applicable,
may be required.
2. Leave Travel Concession/Assistance
- Where eligible, the employee may furnish the prescribed particulars/evidence relating to the claim.
3. Interest on Housing Loan
Where the applicable provisions permit consideration of interest on borrowed capital, the employee may furnish relevant details such as:
- Name of lender;
- Address of lender;
- PAN of lender; and
- Amount of interest.
4. Eligible Deductions
- The employee may furnish particulars and supporting evidence for deductions that are permissible under the applicable tax regime and provisions.
Form-125: Statement of Particulars of Perquisites, Other Fringe Benefits or Amenities and Profits in Lieu of Salary
It is a statement containing particulars of:
- Perquisites;
- Other fringe benefits or amenities; and
- Profits in lieu of salary,
along with their prescribed values.
The employer is required to determine the value of taxable perquisites and other relevant benefits in accordance with the applicable provisions and furnish the prescribed statement to the employee.
Examples of perquisites may include:
- Rent-free accommodation;
- Motor car facilities;
- ESOP-related benefits;
- Concessional loans;
- Other taxable benefits or amenities.
The value of taxable perquisites is considered while determining the employee’s salary income for TDS purposes.
Difference Between Form 122, Form 124 and Form 125