Case Study 2
Company Information:
- Company Name: Finc Technologies Private Limited
- TAN Number: DELI14724D
- Address: #67, 2nd Cross, Rajpath Marg, Rajpath Nagar, New Delhi 110001
- PAN Number: JHKCG2872H
TDS Login Details (Income Tax Website):
- User ID: DELI14724D
- Password: Fin@123
Transactions:
1. On 1st April, Company entered into agreement with M/s. Keshav & Family (HUF) for carrying out the work as mentioned in contract and contract amount is ₹59,000. On 30th April, Company is making payment of ₹25,000. Balance paid on 15th June.
2. On 15th April, Entered into an agreement with M/s. Neo Tools Pvt Ltd for a contract value of ₹1,25,000. Percentage of completion of the contract for invoicing and payment details are given below:
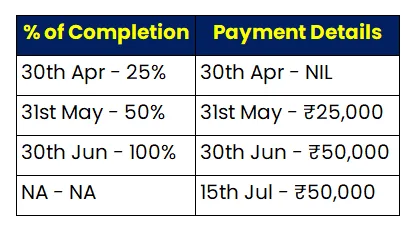
3. On 5th May, Company paid commission to Mr. Umesh amounting to ₹19,500.
4. Company pays monthly building rent of ₹22,000 to Mr. Narayana on the 5th of the following month, with invoices dated the last day of the previous month.
5. Company rents a Machinery from M/s. Bhumi Machineries Pvt Ltd for 6 months (April to September) at ₹50,000/month. Payments are made in advance on the 1st of every month, invoices are dated end of the month.
6. On 15th April, Company paid ₹25,000 as professional fees to CS Mr. Narayan K without deducting TDS. Another bill of ₹10,000 was received on 30th June.
7. On 2nd May, ₹88,500 (incl. GST @18%) paid to Mr. Naveen towards technical services bill dated 30th April.
8. On 30th April, entered into catering contract with Mr. Suresh Gowda (Individual) for ₹1,05,000. ₹20,000 advance paid on same day; balance paid on 17th June upon completion.
9. On 30th April, bill from G B A & Associates for internal audit fee ₹41,300 (including GST ₹6,300). Fee revised to ₹47,200 (incl. GST) from May onward.
10. Factory godown rent ₹21,240/month (incl. GST @18%) is paid to Mr. Nadhish Kumar. Also, rent towards machinery ₹1,18,000/month (incl. GST) for April to June.
Statement showing TDS to be deducted of Finc Technologies Private Limited:
| Date | Party | Section – Income-tax Act, 2025 | Amount | TDS Rate | TDS Amount | Month | Due Date | Remarks |
|---|---|---|---|---|---|---|---|---|
| 30-Apr | M/s. Keshav & Family (HUF) | 393 – Contractor | ₹25,000 | 1% | Nil | Apr | — | April payment below ₹30,000 single-payment threshold |
| 31-May | M/s. Neo Tools Pvt Ltd | 393 – Contractor | ₹25,000 | 2% | Nil | May | — | Aggregate till May ₹25,000; threshold of ₹1,00,000 not exceeded |
| 30-Jun | M/s. Keshav & Family (HUF) | 393 – Contractor | ₹34,000 | 1% | ₹340 | Jun | 07-Jul | June payment exceeds ₹30,000; TDS on entire June payment |
| 30-Jun | M/s. Neo Tools Pvt Ltd | 393 – Contractor | ₹50,000 | 2% | Nil | Jun | — | Aggregate till June ₹75,000; ₹1,00,000 threshold not exceeded |
| 05-May | Mr. Umesh | 393 – Commission/Brokerage | ₹19,500 | 2% | Nil | May | — | Amount does not exceed ₹20,000 threshold |
| 30-Apr | Mr. Narayana | 393 – Rent | ₹22,000 | 10% | Nil | Apr | — | Building rent below ₹50,000 per month threshold |
| 31-May | Mr. Narayana | 393 – Rent | ₹22,000 | 10% | Nil | May | — | Monthly rent below threshold |
| 30-Jun | Mr. Narayana | 393 – Rent | ₹22,000 | 10% | Nil | Jun | — | Monthly rent below threshold |
| 30-Apr | M/s. Bhumi Machineries Pvt Ltd | 393 – Rent | ₹50,000 | 2% | Nil | Apr | — | Machinery rent exactly ₹50,000; threshold not exceeded |
| 31-May | M/s. Bhumi Machineries Pvt Ltd | 393 – Rent | ₹50,000 | 2% | Nil | May | — | Machinery rent exactly at threshold |
| 30-Jun | M/s. Bhumi Machineries Pvt Ltd | 393 – Rent | ₹50,000 | 2% | Nil | Jun | — | Machinery rent exactly at threshold |
| 15-Apr | CS Mr. Narayan K | 393 – Professional Services | ₹25,000 | 10% | Nil | Apr | — | Aggregate professional fee below ₹50,000 |
| 30-Jun | CS Mr. Narayan K | 393 – Professional Services | ₹10,000 | 10% | Nil | Jun | — | Aggregate ₹35,000; threshold of ₹50,000 not exceeded |
| 02-May | Mr. Naveen | 393 – Technical Services | ₹75,000 | 2% | ₹1,500 | May | 07-Jun | ₹88,500 incl. GST; TDS on ₹75,000 excluding GST |
| 30-Apr | Mr. Suresh Gowda | 393 – Contractor/Catering | ₹20,000 | 1% | Nil | Apr | — | Advance below ₹30,000; aggregate threshold not yet exceeded |
| 17-Jun | Mr. Suresh Gowda | 393 – Contractor/Catering | ₹85,000 | 1% | ₹1,050 | Jun | 07-Jul | Aggregate contract ₹1,05,000 exceeds ₹1,00,000; TDS on entire contract |
| 30-Apr | G B A & Associates | 393 – Professional Services | ₹35,000 | 10% | Nil | Apr | — | Aggregate professional fee below ₹50,000 at this stage |
| 31-May | G B A & Associates | 393 – Professional Services | ₹40,000 | 10% | ₹7,500 | May | 07-Jun | Aggregate ₹75,000 exceeds ₹50,000; TDS on entire ₹75,000 |
| 30-Jun | G B A & Associates | 393 – Professional Services | ₹40,000 | 10% | ₹4,000 | Jun | 07-Jul | Additional June professional fee; TDS @10% |
| 30-Apr | Mr. Nadhish Kumar | 393 – Rent | ₹18,000 | 10% | Nil | Apr | — | Building rent excluding GST below ₹50,000/month |
| 31-May | Mr. Nadhish Kumar | 393 – Rent | ₹18,000 | 10% | Nil | May | — | Monthly rent below threshold |
| 30-Jun | Mr. Nadhish Kumar | 393 – Rent | ₹18,000 | 10% | Nil | Jun | — | Monthly rent below threshold |
| 30-Apr | Machinery Vendor | 393 – Rent | ₹1,00,000 | 2% | ₹2,000 | Apr | 07-May | Machinery rent excluding GST ₹1,00,000; exceeds ₹50,000 |
| 31-May | Machinery Vendor | 393 – Rent | ₹1,00,000 | 2% | ₹2,000 | May | 07-Jun | Monthly machinery rent exceeds threshold |
| 30-Jun | Machinery Vendor | 393 – Rent | ₹1,00,000 | 2% | ₹2,000 | Jun | 07-Jul | Monthly machinery rent exceeds threshold |
| 15-Jul | M/s. Neo Tools Pvt Ltd | 393 – Contractor | ₹50,000 | 2% | ₹2,500 | Jul | 07-Aug | Aggregate contract ₹1,25,000 exceeds ₹1,00,000; TDS on entire ₹1,25,000 |
Notes:
1. Payment to M/s. Keshav & Family (HUF)
The payment made to M/s. Keshav & Family, an HUF, is covered under Section 393(1), Table Sl. No. 6(i) of the Income-tax Act, 2025, relating to payments to contractors for carrying out work. Since the contractor is an HUF, TDS is applicable at 1%. The agreement value is ₹59,000. The first payment of ₹25,000 made on 30 April is below the single-payment threshold of ₹30,000 and therefore no TDS is required on that payment. The balance amount of ₹34,000 paid on 15 June exceeds the ₹30,000 threshold. Accordingly, TDS is required at 1% on ₹34,000, amounting to ₹340. The ₹1,00,000 aggregate threshold should not be confused with the ₹30,000 individual-payment threshold.
2. Payment to M/s. Neo Tools Pvt. Ltd.
The contract with M/s. Neo Tools Pvt. Ltd. is covered under Section 393(1), Table Sl. No. 6(i). Since the contractor is a company, TDS is applicable at 2%. The payments are ₹25,000 in May, ₹50,000 in June and ₹50,000 in July. The first payment of ₹25,000 is below ₹30,000, and although the June payment is ₹50,000, the cumulative amount up to June is ₹75,000, which is below the aggregate threshold of ₹1,00,000. Therefore, no TDS is required up to June. The July payment takes the aggregate contract payments to ₹1,25,000, exceeding the ₹1,00,000 threshold. Consequently, TDS is required on the entire ₹1,25,000 at 2%, resulting in ₹2,500 TDS. Since the threshold is crossed only in July, this amount falls outside the first quarter.
3. Commission paid to Mr. Umesh
The commission paid to Mr. Umesh is covered under Section 393(1), Table Sl. No. 1(ii) of the Income-tax Act, 2025, relating to commission or brokerage. The applicable TDS rate is 2%, subject to the threshold of ₹20,000. Since the commission paid is only ₹19,500, it does not exceed the prescribed threshold. Therefore, no TDS is required on the commission payment of ₹19,500.
4. Building rent paid to Mr. Narayana
The monthly building rent of ₹22,000 paid to Mr. Narayana is covered under Section 393(1), Table Sl. No. 2(ii) relating to rent. For rent of land, building, furniture or fittings, the applicable TDS rate is 10%, with a threshold of ₹50,000 for a month or part of a month. Since the monthly rent is only ₹22,000, it does not exceed the prescribed monthly threshold. Therefore, no TDS is required on the rent paid to Mr. Narayana. The fact that the rent is paid every month does not by itself create TDS liability when the monthly threshold is not exceeded.
5. Machinery rent paid to M/s. Bhumi Machineries Pvt. Ltd.
The machinery rent paid to M/s. Bhumi Machineries Pvt. Ltd. is covered under Section 393(1), Table Sl. No. 2(ii). Rent for machinery, plant or equipment attracts TDS at 2%, subject to the threshold of ₹50,000 for a month or part of a month. In this case, the monthly machinery rent is exactly ₹50,000. Since the provision requires the amount to exceed ₹50,000, an amount exactly equal to ₹50,000 does not trigger TDS. Therefore, no TDS is required on the monthly machinery rent, even though the total rent for six months is ₹3,00,000.
6. Professional fees paid to CS Mr. Narayan K
The professional fees paid to CS Mr. Narayan K are covered under Section 393(1), Table Sl. No. 6(iii) relating to professional services. The applicable TDS rate for professional services is 10%, with a threshold of ₹50,000. The first professional fee of ₹25,000 paid in April is below the threshold. A further bill of ₹10,000 is received in June, taking the total professional fees during the tax year to ₹35,000. Since the aggregate amount of ₹35,000 is still below ₹50,000, no TDS is required. Accordingly, the payment made in April without deducting TDS does not constitute a TDS default based on the facts given.
7. Technical service fee paid to Mr. Naveen
The payment to Mr. Naveen is for technical services and is covered under Section 393(1), Table Sl. No. 6(iii). Technical services, other than professional services, attract TDS at 2%, subject to a threshold of ₹50,000. The invoice amount is ₹88,500 inclusive of GST at 18%. Where GST is separately indicated in the invoice, TDS is calculated on the amount excluding GST. Therefore, the taxable service value is ₹88,500 ÷ 1.18 = ₹75,000. Since ₹75,000 exceeds the ₹50,000 threshold, TDS is required at 2%. Accordingly, TDS payable is ₹1,500.
8. Catering contract with Mr. Suresh Gowda
The catering contract with Mr. Suresh Gowda is covered under Section 393(1), Table Sl. No. 6(i) because catering is included within the definition of “work” under Section 402(47). Since Mr. Suresh Gowda is an individual contractor, TDS is applicable at 1%. The initial advance of ₹20,000 paid on 30 April is below the ₹30,000 single-payment threshold, so no TDS is required at that stage. However, the subsequent payment of ₹85,000 takes the aggregate contract value to ₹1,05,000, exceeding the aggregate threshold of ₹1,00,000. Once the threshold is exceeded, TDS is applicable on the entire contract amount of ₹1,05,000. Therefore, TDS at 1% amounts to ₹1,050, which is deducted/recovered from the subsequent payment.
9. Internal audit fees paid to G B A & Associates
The internal audit fees paid to G B A & Associates are covered under Section 393(1), Table Sl. No. 6(iii) as professional services. The applicable TDS rate is 10%, with a threshold of ₹50,000. The April invoice is ₹41,300 including GST of ₹6,300, giving a professional fee of ₹35,000 excluding GST. Since ₹35,000 is below the threshold, no TDS is required in April. From May onwards, the fee is ₹47,200 including GST, equivalent to ₹40,000 excluding GST. The May payment takes the aggregate professional fee to ₹75,000, thereby crossing the ₹50,000 threshold. Hence, TDS is applicable on the entire cumulative amount of ₹75,000 at 10%, resulting in ₹7,500 TDS in May. The June professional fee of ₹40,000 attracts further TDS of ₹4,000. Therefore, total TDS for the first quarter on these professional fees is ₹11,500.
10. Rent paid to Mr. Nadhish Kumar and machinery rent
The factory godown rent paid to Mr. Nadhish Kumar is covered under Section 393(1), Table Sl. No. 2(ii). The monthly amount of ₹21,240 includes GST at 18%. Excluding GST, the rent is ₹18,000 per month. Since this is below the ₹50,000 monthly threshold applicable to building rent, no TDS is required on the godown rent. However, the separate machinery rent of ₹1,18,000 per month, including GST, is also covered under the same provision. Excluding GST, the machinery rent is ₹1,00,000 per month. Since this exceeds the ₹50,000 threshold applicable to machinery, plant or equipment rent, TDS is required at 2% of ₹1,00,000, i.e. ₹2,000 per month. For April, May and June, the total TDS on machinery rent is therefore ₹6,000.
TDS to be deducted:
| Section | April | May | June | July | Grand Total |
|---|---|---|---|---|---|
| 393 – Contractor | ₹0 | ₹0 | ₹1,390 | ₹2,500 | ₹3,890 |
| 393 – Commission/Brokerage | ₹0 | ₹0 | ₹0 | ₹0 | ₹0 |
| 393 – Rent | ₹2,000 | ₹2,000 | ₹2,000 | ₹0 | ₹6,000 |
| 393 – Professional Services | ₹0 | ₹7,500 | ₹4,000 | ₹0 | ₹11,500 |
| 393 – Technical Services | ₹0 | ₹1,500 | ₹0 | ₹0 | ₹1,500 |
| Grand Total | ₹2,000 | ₹11,000 | ₹7,390 | ₹2,500 | ₹22,890 |