Case Study 1
Task to Complete:Compute TDS deductible by the Company for each case separately in the 1st Quarter of the current tax yearPay TDS using simulation software
Company Details:
- Company Name: Finc Power Source Private Limited
- TAN Number: BLRG22875G
- Address: Address: 2870, Phoenix Building, Bagmane Business Park, Outer Ring Road, Marathahalli Post, Bangalore – 560037
- PAN Number: NHNCG2827L
TDS Login Details (Income Tax Website):
- User ID: BLRG22875G
- Password: Fin@123
Click here to Access Simulation Software to make TDS Payment🔗
Based on the transactions executed by Finc Power Source Private Limited during Q1, analyze the TDS implications under the provisions of the Income-tax Act, 2025 and calculate the applicable tax to be deducted at source for each case:
- Loan Interest PaymentOn 17th April, interest of 18% p.a. on a loan of ₹25,00,000 taken from M/s. VR Finance Co. (a Non-Banking Financial Company) was payable monthly. Determine the TDS applicability, threshold limit, and deduction amount under Section 392.
- Advertising Service ContractOn 1st May, a contract for advertisement services was entered with M/s Justdial Ltd for ₹18,000 per month. Analyze whether TDS is deductible for Q1 payments under Section 393 considering the revised single and aggregate contract thresholds.
- Catering Service ContractOn 1st May, a catering contract for 3 months was entered with Ravishankar Caterers (a sole proprietorship) for a total amount of ₹37,500 (₹12,500/month) to be billed after completion. Evaluate the TDS liability under Section 393 against the updated statutory limits.
- Commercial Property RentMonthly office rent of ₹20,000 for April and May and ₹25,000 for June (totaling ₹65,000 during Q1) was paid to Mr. Naveen H. Determine the applicability of TDS under Section 396(1)(b) based on the revised annual monetary limit.
- Audit and Professional FeesOn 17th June, professional charges of ₹35,000 were paid to M/s G B A & Associates (a partnership firm of auditors). Calculate the required TDS, if any, under Section 398.
- Digital Marketing FeesOn 30th June, ₹55,000 was paid to ABC Digital Agency (a proprietorship) for digital marketing services. Classify the nature of service and determine the applicable TDS rate and amount under Section 398.
- Purchase of GoodsPurchases worth ₹58,00,000 were made during Q1 from Mega Distributors Pvt Ltd (a resident seller). Assuming Finc Power Source Private Limited’s turnover in the preceding financial year exceeded ₹10 Crore, compute the TDS liability under Section 401.
- Agent CommissionOn 15th June, a commission of ₹25,000 was paid to Harish Bafna, an individual agent. Determine the applicable TDS rate and deduction under Section 395.
- Lease BrokerageOn 25th April, ₹70,000 was paid to Royal Realtors as brokerage for leasing office space. Calculate the TDS to be deducted under Section 395.
- Machinery Hire ChargesOn 15th June, rent of ₹60,000 was paid for machinery taken on lease from Venkat Engineering. Evaluate the TDS obligation under Section 396(1)(a).
Solution:
Statement showing TDS to be deducted of Finc Power Source Private Limited:
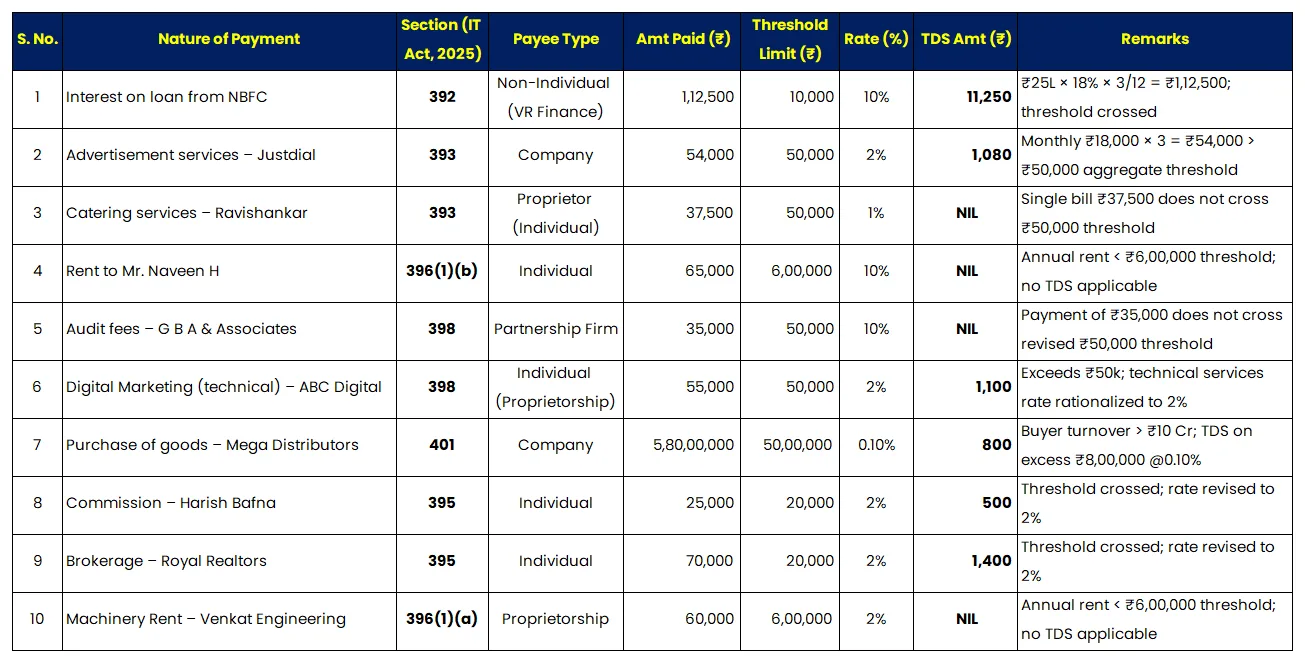
TDS Summary Table
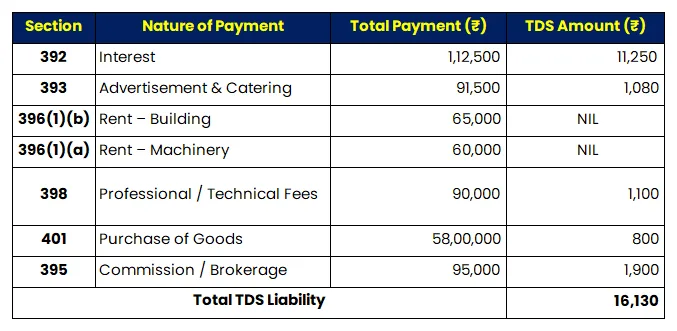
Notes:
- Interest from NBFC – Section 392 Interest paid to Non-Banking Financial Companies is governed by Section 392. Under the updated provisions, the monetary threshold for non-bank interest deduction is revised to ₹10,000. Total interest payable for 3 months on ₹25,00,000 at 18% p.a. is ₹1,12,500, crossing the threshold. TDS @10% applies, amounting to ₹11,250.
- Advertisement to Justdial – Section 393 Contractual payments for advertisement fall under Section 393. The revised threshold for contractual payments is ₹50,000 for a single contract or ₹2,00,000 in aggregate. Justdial’s contract of ₹18,000/month for 3 months totals ₹54,000, exceeding the single-contract threshold of ₹50,000. As a company entity, TDS @2% is applicable, resulting in a deduction of ₹1,080.
- Catering Bill by Ravishankar – Section 393 Catering contracts are treated as works contracts under Section 393. Since the single bill for 3 months amounts to ₹37,500, it remains below the updated single transaction threshold of ₹50,000 (and aggregate threshold of ₹2,00,000). Consequently, no TDS is deductible.
- Rent to Mr. Naveen H – Section 396(1)(b) Rent paid for land or building to individuals/entities is covered under Section 396(1)(b). Under the unified framework, the threshold limit for rent deduction is updated to ₹6,00,000 annually. Since the payment during Q1 is ₹65,000 (and total annual projected rent is ₹2,60,000), it falls well below the statutory threshold of ₹6,00,000. Hence, no TDS is required.
- Audit Fee to Partnership Firm – Section 398 Audit and professional fees fall under Section 398. The basic threshold for professional services is revised to ₹50,000 per financial year. Because the payment of ₹35,000 made to M/s G B A & Associates does not exceed ₹50,000, no TDS is deductible under Section 398.
- Digital Marketing to ABC Digital – Section 398 Digital marketing involving technical interfaces or data processing is classified under fees for technical services under Section 398. The payment of ₹55,000 exceeds the revised single/aggregate threshold of ₹50,000. Under the simplified structure, technical services attract a reduced TDS rate of 2% (down from 10%), resulting in a deduction of ₹1,100.
- Goods Purchase – Section 401 Section 401 requires buyers with turnover exceeding ₹10 Crore in the preceding fiscal year to deduct TDS @0.1% on purchase of goods from resident sellers exceeding ₹50 Lakhs in a year. For purchases of ₹58,00,000 from Mega Distributors, TDS is computed on the excess amount of ₹8,00,000 (₹58,00,000 – ₹50,00,000) at 0.10%, which equals ₹800.
- Commission to Harish Bafna – Section 395 Section 395 governs commission and brokerage payments. The revised threshold limit is ₹20,000, and the statutory TDS rate is simplified to 2% (down from 5%). Payment of ₹25,00,000 to Harish exceeds the threshold, requiring TDS @2% equal to ₹500.
- Brokerage to Royal Realtors – Section 395 Brokerage paid for real estate leasing falls under Section 395. The payment of ₹70,000 exceeds the ₹20,000 threshold. Applying the revised rate of 2% yields a TDS deduction of ₹1,400.
- Machinery Rent to Venkat Engineering – Section 396(1)(a) Rent paid for plant, machinery, or equipment is governed by Section 396(1)(a). The applicable annual threshold is ₹6,00,000. Since the lease payment of ₹60,000 is significantly below ₹6,00,000, no TDS is deductible.